CWS Market Review – September 22, 2026
(This is the free version of CWS Market Review. If you like what you see, then please sign up for the premium newsletter for $20 per month or $200 for the whole year. If you sign up today, you can see our two reports, “Your Handy Guide to Stock Orders” and “How Not to Get Screwed on Your Mortgage.”)
The stock market has been in a relatively buoyant mood this week. The S&P 500 narrowly missed closing higher for four days in a row. In fact, Wednesday was the market’s best day in seven weeks, and it’s very close to another all-time high. The current all-time high was set on August 13. Over that time, the market had a brief 3.2% drawdown; and we’ve nearly made it all back.
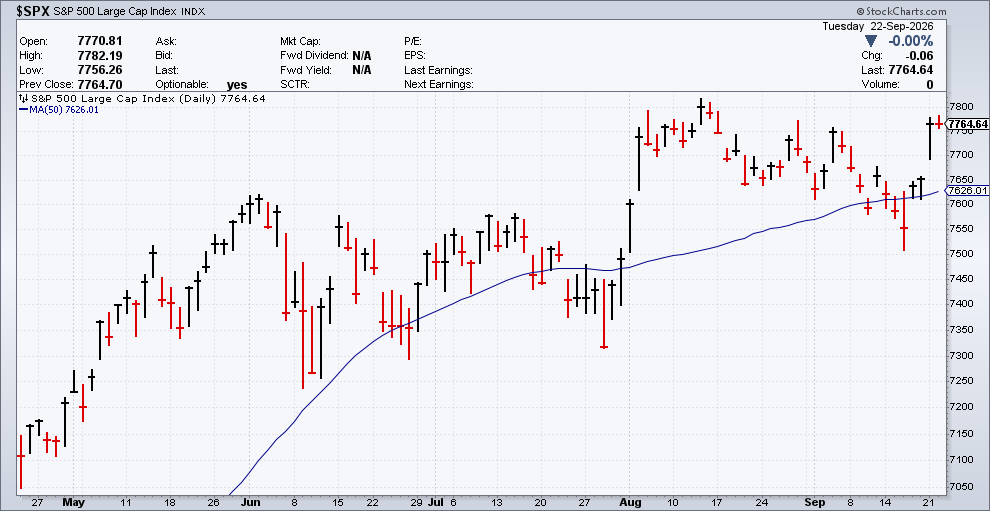
The Nasdaq has been even more impressive. That index reached an all-time high today. The tech-heavy index reached its previous all-time high in June. If you recall, the Nasdaq had a 10% drawdown during June and July. Once again, we made it all back.
The market has swung sharply in favor of growth stocks. This continues a trend that started in late July. Typically, higher short-term interest rates from the Fed work to punish rate-sensitive and high-duration stocks, and that’s exactly what we’ve seen.
For example, the S&P 500 Utility Index (XLU) just touched a new 52-week low. This is happening at the same time that the S&P 500 Growth Index (SPYG) is at a new 52-week high. It’s not so much the fault of the Federal Reserve, but the market is reacting to the same forces the Fed is facing.
Make no mistake: this is still a market that’s fixated on AI. Advanced Micro Devices (AMD) just became the latest $1 trillion company. There are now 12 stocks in the “Four Comma Club.” Expect to see more.
The folks at FactSet broke down the earnings calls from the most recent earnings season. They found that the term “AI” was referenced in two-thirds of the earnings calls. This was the third quarter in a row that AI has appeared on more than 65% of earnings calls. AI was mentioned on 97% of tech earnings calls.
As you might guess, the AI trade is back. Shares of Meta (META) rallied 11% after its new Muse AI agent became #1 at the App Store. Intel (INTC) jumped about 12%, and several other chip and tech names followed.
The Treasury bond market eased up a bit today. The yield on the 10-year Treasury fell below 5%. The Federal Reserve doesn’t meet again for another five weeks, but traders are already speculating on the Fed’s next move. For now, traders are nearly 50-50 on the idea of the Fed hiking rates in October.
Frankly, we’re also in a bit of a slow patch for economic news. This week, we’ll get reports on new-home sales and jobless claims. Next week will be more newsworthy as we’ll get the GDP report and the September jobs report.
The U.S. unemployment rate has been below 4.5% nearly every month for the past four years. In previous times, that would be considered remarkable. Now, it seems like everyone is nervous and pessimistic. Charlie Bilello points out that the unemployment rate has now been below 5% for 60 months in a row. That’s the longest streak since the 1960s.
In the last 17 years, the U.S. economy has been in one two-month recession, and that was due to Covid. We haven’t seen a recession that started for purely economic reasons since 2008. Despite this, all the polls indicate that Americans are quite pessimistic on our future prospects.
Check out this chart of the S&P 500 Growth Index (blue) versus the S&P 500 Value Index (green).
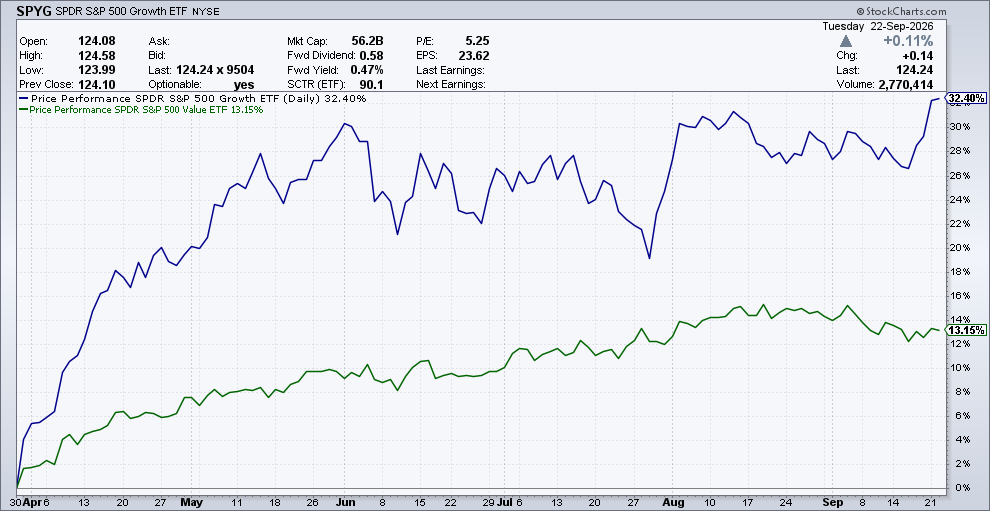
Except for a sharp reversal in June and July, growth has been beating value. Notice how stable the value line is compared with the frenetic growth line.
This highlights an important truth: there are a lot of companies that are being left out of this rally. The problem with such a narrow rally is that it can easily be reversed. Close to 190 stocks in the S&P 500 are more than 20% off their 52-week highs.
Half the stocks in the S&P 500 Energy Index are more than 10% off their 52-week highs, and several of those are more than 20% off. Texas Pacific Land Corporation (TPL) is down more than 30%.
Q3 Earnings Season Preview
Next week, the third quarter of 2026 comes to an end, and the Q3 earnings season will begin shortly after. The unofficial kickoff for Q3 earnings season will be Tuesday, October 13. That’s when JPMorgan (JPM), Wells Fargo (WFC), Citigroup (C) and Goldman Sachs (GS) are due to report. Usually, the big banks are the first to report. A handful of companies with August fiscal year-ends have already reported (Oracle, Adobe and Lennar).
Expectations for Q3 are quite high. The Q2 earnings season was quite good. There had been some nervousness that expectations may have been too high, but that turned out not to be the case.
The number crunchers at FactSet expect Q3 revenue growth of 11.9%, and earnings growth of 28.7%. If that’s right, then it will mark the third quarter in a row in which earnings growth topped 25%.
Interestingly, estimates have been revised higher since the middle of the year. At last count, positive guidance is outrunning negative guidance, 72 to 42. Typically, the reverse happens. Earnings estimates are pared back until earnings season. That lets companies lower the bar until they can easily jump over it. On Planet Wall Street, it’s all a big expectations game.
One positive aspect is that earnings growth appears to be broader and not just mega-cap tech stocks, even though stock prices aren’t reflecting this. The big winner looks to be the energy sector. Thanks to high prices, earnings are expected to double. Obviously, tech is a big player. Earnings at Nvidia (NVDA) are expected to be up 90%. Micron (MU) is expected to be up triple digits as well. MU is due to report after the close one week from tomorrow.
Wall Street expects decent gains for areas like materials, aerospace and transportation. Consumer staples are expected to be flat. If you take out energy, then overall growth falls to the low 20% range. Take out tech, and it falls even more.
In particular, investors will focus on capex spending by the mega-cap names. On top of that, we have geopolitical risks that could impact the market. Overall, the bar is set high for earnings. Expect to see a lot of “earnings beats,” but we want to hear positive guidance for the rest of 2026.
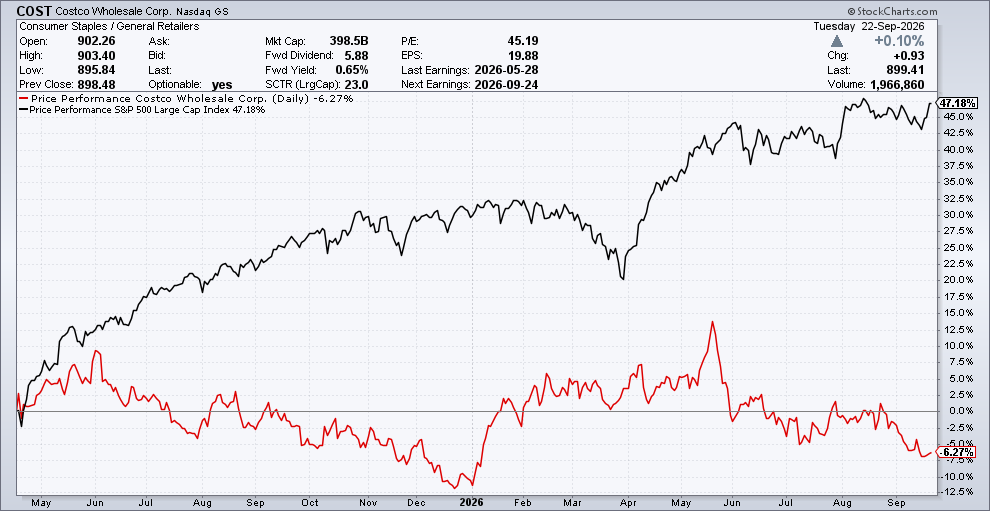
Also, keep an eye on Costco (COST). The store will release earnings after the close on Thursday. Shares of COST haven’t been that strong recently, which is rare for them. Over the last 16 months, the S&P 500 is up 47% while COST is down 6%. Is it a bargain? I’m not so sure. Even after the downturn, COST trades at 40 times next year’s earnings. On Wall Street, even the best stocks will hit rough patches.
That’s all for now. The new-home sales report is due out on Thursday along with the regular jobless claims report. I’ll have more for you in the next issue of CWS Market Review.
– Eddy
Posted by Eddy Elfenbein on September 22nd, 2026 at 5:05 pm
The information in this blog post represents my own opinions and does not contain a recommendation for any particular security or investment. I or my affiliates may hold positions or other interests in securities mentioned in the Blog, please see my Disclaimer page for my full disclaimer.
-
Archives
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His