CWS Market Review – October 6, 2026
(This is the free version of CWS Market Review. If you like what you see, then please sign up for the premium newsletter for $20 per month or $200 for the whole year. If you sign up today, you can see our two reports, “Your Handy Guide to Stock Orders” and “How Not to Get Screwed on Your Mortgage.”)
On Tuesday, the stock market rallied for the fourth day in a row, and the S&P 500 reached a new all-time high. It took nearly two months for the market to surpass its previous high from August 13. Over the last four years, the S&P 500 is up 109%. Growth stocks have been especially popular. Since July 30, the S&P 500 Growth ETF (SPYG) is up by 13.4%.
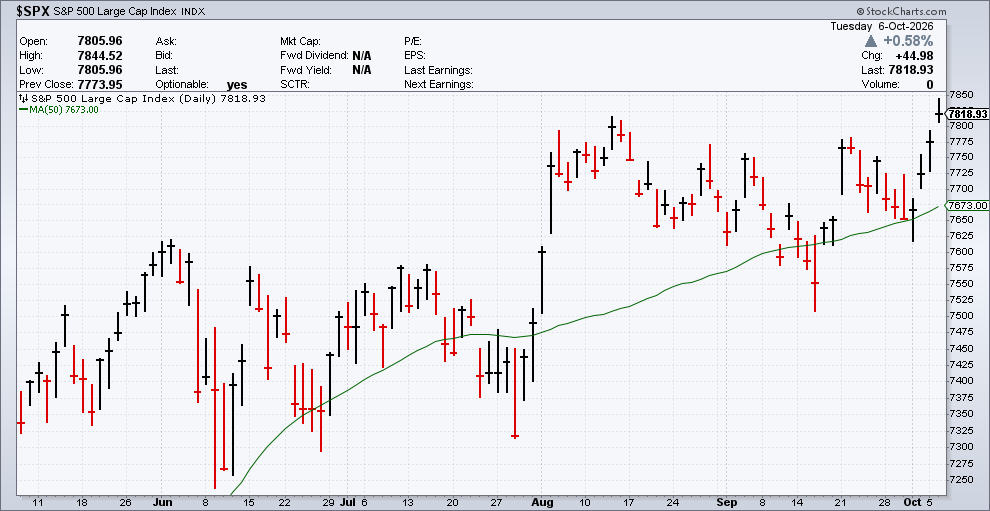
I always find it fascinating how easily the stock market can ignore scary headlines and calmly march higher. The stock market indeed climbs a wall of worry. The latest worry is in the bond market. Earlier today, the yield on the 10-year Treasury topped 5.35%. That’s up 70 basis points over the last month.
The impact of higher rates is real. With rates so high, more Americans are choosing to stay put. Homeowners are sitting on record amounts of home equity, but they’re choosing to not use it.
There’s a lot to get to this week, so let’s first look at Friday’s jobs report which has forced the Federal Reserve to hold off its rate-hiking plans for now.
A Big Miss for the September Jobs Report
Wall Street got a big shock on Friday when the Bureau of Labor Statistics said that the U.S. economy created just 29,000 net new jobs last month. Economists had been expecting a gain of 84,000 jobs. The unemployment rate rose to 4.2%. That was 0.1% higher than expected.
The monthly unemployment rate has been below 5% for the last 61 months in a row. That includes the government shutdown month of October 2025. That’s the longest streak since the 64-month run from March 1965 to June 1970.
The numbers for August were revised lower. The combined revisions showed a new loss of 60,000 jobs. July flipped to a loss of 10,000 jobs. Over the last 18 months, the U.S. economy has created 667,000 new jobs. Over the 18 months prior to that, the economy created 1.96 million jobs.
Here’s a look at the growth of non-farm payrolls:
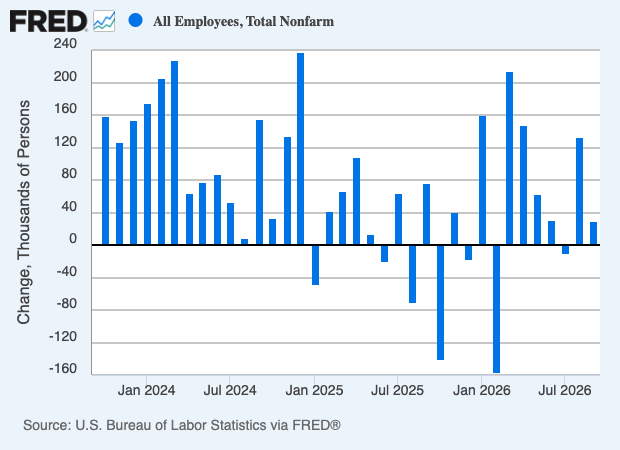
Once the jobs report came out, traders rushed to change their bets on the odds of another Fed rate increase. The Fed meets again three weeks from tomorrow. Traders now place an 80% chance that the Fed will hold rates steady. In retrospect, it looks like the strong number we originally had for August was an outlier.
Here are some of the details from the report:
Most of the monthly job gains came from healthcare, which added 17,000 workers. Construction was up by 11,000, and manufacturing added 9,000.
Government employment fell by 17,000, while temporary help services saw a decline of 11,000, and information services lost 10,000 amid worries over the impact artificial intelligence may have on the jobs picture. Financial activities also saw a drop of 7,000 jobs.
The labor force participation rate increased by 0.2% to 61.8%. That was its highest reading since May. The broader U-6 unemployment rate dropped slightly to 7.6%.
I’m still concerned about wages. The jobs report said that average hourly earnings rose by 0.1% last month. Wall Street had been expecting 0.1%. Over the last 12 months, wages are up by 3%. That’s the slowest growth rate in five years. The average work week was unchanged at 34.6 hours.
This report gives the Fed political cover to leave rates alone at this month’s meeting. After that, there’s still a good chance the Fed will hike in December. In other words, the jobs report merely delays the Fed, but it doesn’t change the Fed’s gameplan.
The next big event to consider is the upcoming earnings season. Here’s a preview of some of the big bank earnings coming our way.
The Big Banks Report Next Week
The third-quarter earnings season has its unofficial kickoff next week. On Tuesday, October 13, several major banks are due to report their earnings. This includes JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo.
Let’s take a close look at what to expect. JPMorgan Chase (JPM) is the biggie, and everyone wants to hear what Jamie Dimon has to say about the economy and the banking sector.
Analysts will be watching for loan growth, consumer credit and net interest income. For now, the consensus on Wall Street is that JPM will make $5.90 per share on revenue of $51 billion. Oppenheimer recently nudged its JPM estimate higher and JPM is the only large bank it expects to beat the Street.
Next up is Goldman Sachs (GS). This is another titan of Wall Street. The consensus is for EPS of $13.50 to $14.30 per share on revenue of $17 billion. The keys to watch out for are trading and investment-banking fees. GS has beaten estimates in each of the last four quarters.
Goldman is the purest read on capital markets. Trading has been the stronger leg with investment-banking fees looking softer. Oppenheimer cut its investment banking revenue view by 9.5% while lifting trading by about 6%, and it cut EPS forecasts for Goldman, Morgan Stanley, Bank of America and Citigroup. A miss on advisory or equity underwriting would hit Goldman harder than it would a universal bank.
Citigroup (C). Oh boy, what to say? Citi is still in the middle of a long-term cleanup. Management has guided full-year 2026 return on tangible common equity toward a bit above 11%, an efficiency ratio around 60% or better, and NII excluding markets at or above 5% to 6% growth.
Consensus revenue is about $23.7 billion to $23.8 billion versus $22 billion a year earlier. Investors will be watching whether the beat streak on expenses and capital return continues. Consensus is for earnings of $2.65 per share on revenue of $23.7 billion.
Wells Fargo (WFC) is more about core banking: net interest income, commercial loan growth and provisions. EPS consensus is at $1.84 with revenue at $22.3 billion. The EPS rose modestly above the year-ago quarter. Consensus EPS is only modestly above the year-ago quarter.
On Wednesday, Bank of America and Morgan Stanley are due up along with BlackRock.
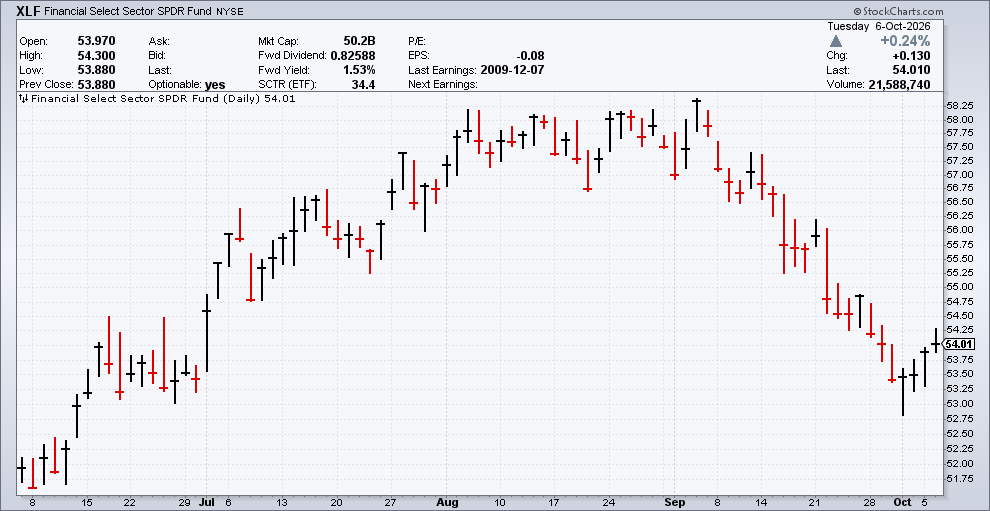
Here’s how the S&P 500 Financials (XLF) have been performing. Not so good lately.
After JPMorgan, Bank of America (BAC) is the cleanest large-scale read on net interest income and consumer/commercial credit. BofA has earnings consensus at $1.11 to $1.17 per share, and revenue between $30.7 and $31.2 billion factoring in net interest income and deposit costs, plus a smaller markets contribution. Fee income and expense trends matter more if NII is stable.
Morgan Stanley (MS) is the wealth-and-markets counterpart to Goldman. Equities and prime brokerage have been strong; advisory is the swing factor. Like Goldman, it is more exposed if deal fees come in light.
Net interest income should still grow year over year, helped by loan growth (especially commercial) and deposit mix, but the rate of improvement has slowed. Credit quality has stayed resilient in recent quarters. Any uptick in card, commercial real estate, or non-bank financial delinquencies would get attention.
It works like this. Market revenue is the upside risk, and investment-banking fees are the downside risk. AI-related financing and hedge-fund borrowing have supported trading and some lending. Morningstar and others have flagged that investment banking and trading revenues look tired and valuations are no longer cheap.
Capital return is a secondary focus featuring buyback pace at Citi and JPMorgan and whether anyone tightens guidance on 2026 net interest income or expenses.
Oppenheimer’s view is the cautious take. Plain-vanilla banking (loans, credit, costs) is fine, but capital-markets revenue is tracking toward the low end of expectations. This means that only JPMorgan is favored to beat, and Wells Fargo is expected to match.
That’s all for now. The stock market will be open on Monday which is Columbus Day, but many schools and offices are closed. I’ll have more for you in the next issue of CWS Market Review.
– Eddy
Posted by Eddy Elfenbein on October 6th, 2026 at 7:18 pm
The information in this blog post represents my own opinions and does not contain a recommendation for any particular security or investment. I or my affiliates may hold positions or other interests in securities mentioned in the Blog, please see my Disclaimer page for my full disclaimer.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His