CWS Market Review – October 13, 2026
(This is the free version of CWS Market Review. If you like what you see, then please sign up for the premium newsletter for $20 per month or $200 for the whole year. If you sign up today, you can see our two reports, “Your Handy Guide to Stock Orders” and “How Not to Get Screwed on Your Mortgage.”)
Today is the unofficial kickoff of Q3 earnings season. Expectations are high and this looks to be another batch of solid earnings from Corporate America.
But, as we well know, Wall Street is an expectations game. For companies to do well, they not only need to post strong earnings, but they must do it stronger than expected. Even meeting expectations can send a stock reeling lower. Many companies expend a great deal of energy guiding analysts to where they want their expectations to be.
In addition to earnings, I’m also curious to hear any guidance companies may have for Q4 and the early part of 2027.
Typically, several of the major banks go first. This is particularly interesting this year because many bank stocks have not done very well over the past month. On top of that, we’re probably looking at another rate increase from the Fed before the end of the year.
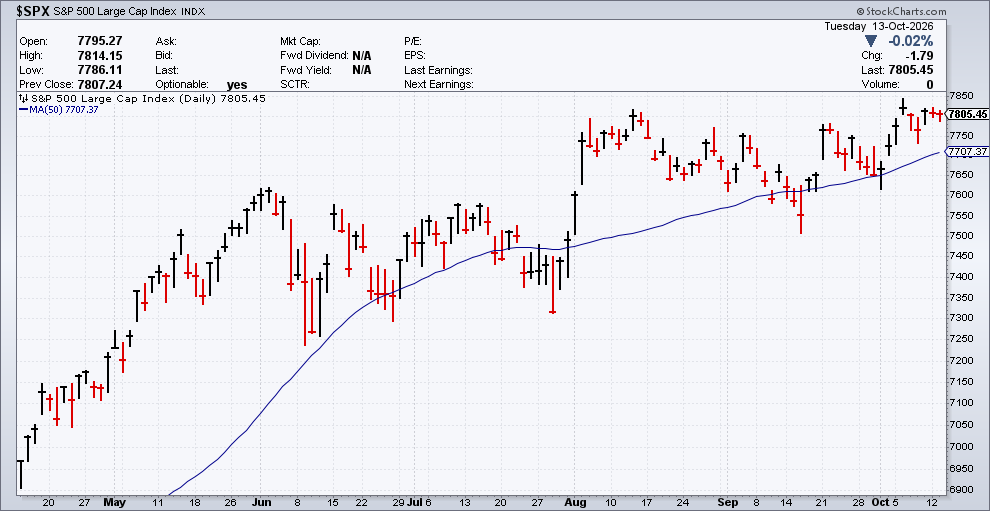
Wall Street closed lower today by a tiny bit. It was the fourth daily drop in the last five sessions, but these have been minor moves. The S&P 500 is still very close to its all-time closing high from one week ago.
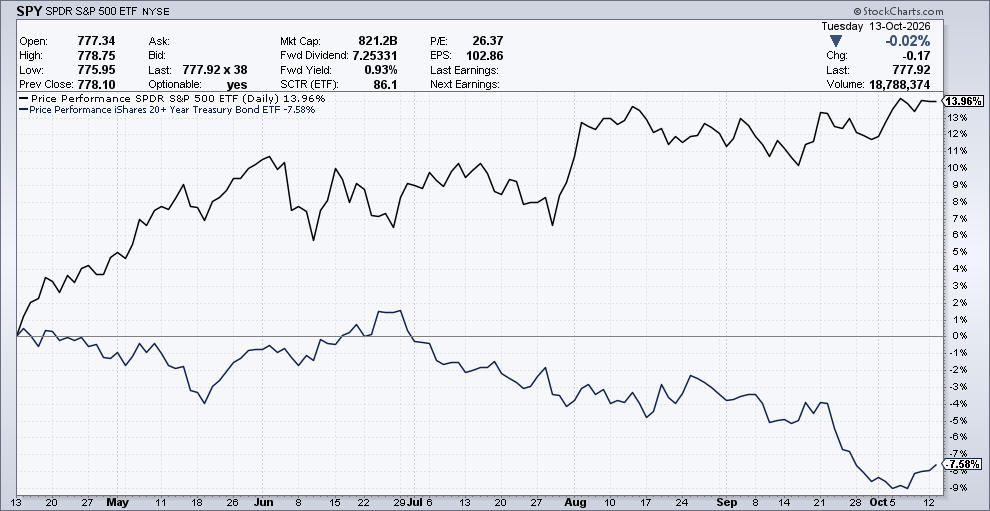
The divergence between the stock and bond markets is still the dominant theme on Wall Street. Over the last six months, the S&P 500 ETF (SPY) has gained 14% while the Long Term Treasury (TLT) is -7.6%. That’s an enormous gulf between the two. The long-term average is about 4% in favor of stocks.
As we stand now, Wall Street expects Q3 earnings growth of 30%. That’s very strong, and if it’s right, then this will go down as the third quarter in a row with +25% earnings growth, and the eighth in a row with double-digit earnings growth.
Another positive sign is that earnings estimates have been climbing higher in recent weeks. That’s not what usually happens. Typically, as earnings season approaches, earnings estimates are gradually pared back. This makes it easier for companies to claim that they “beat the Street.” Yes, a heavily manipulated Street.
We also want to keep an eye on the “beat rate.” Typically, about 75% to 80% of companies beat expectations. So far, 116 companies have issued guidance for Q3. Of those, 62% were positive. That’s well above the long-term average. Revenue growth is expected to be around 12%, and full-year earnings growth is expected to be about 26%, give or take.
When earnings are growing faster than revenue, that means companies are growing their profit margin. That’s good and bad. It generally means that companies are operating more efficiently, but it also means that profits are being goosed by higher prices. That may not be sustainable. To quote Jeff Bezos, “your margin is my opportunity.”
All 11 sectors are expected to report revenue growth for Q3. The forward P/E Ratio is currently around 19, which is higher than I like but not unreasonable, especially if the Fed only hikes a few times.
Now let’s look at some of today’s big bank earnings reports.
The Big Banks Report Q3 Earnings
Let’s start with JPMorgan Chase (JPM), which is the big boy on Wall Street (nearly $900 billion in market cap). This time, JPM posted a small miss. For Q3, JPM made $5.90 per share which was three cents below expectations. Revenue rose 8% which was also a miss. CEO Jamie Dimon said the U.S. economy is holding up well, but he noted risks like inflation, deficits, high asset prices and geopolitics.
Goldman Sachs (GS), another giant on Wall Street, had a strong beat. For Q3, Goldman made $17.01 per share. Expectations were for $13.09 per share. Earnings were up 29% and revenues were up 23% to $18.68 billion. The stock closed lower today, which tells me that traders have set the bar high this season.
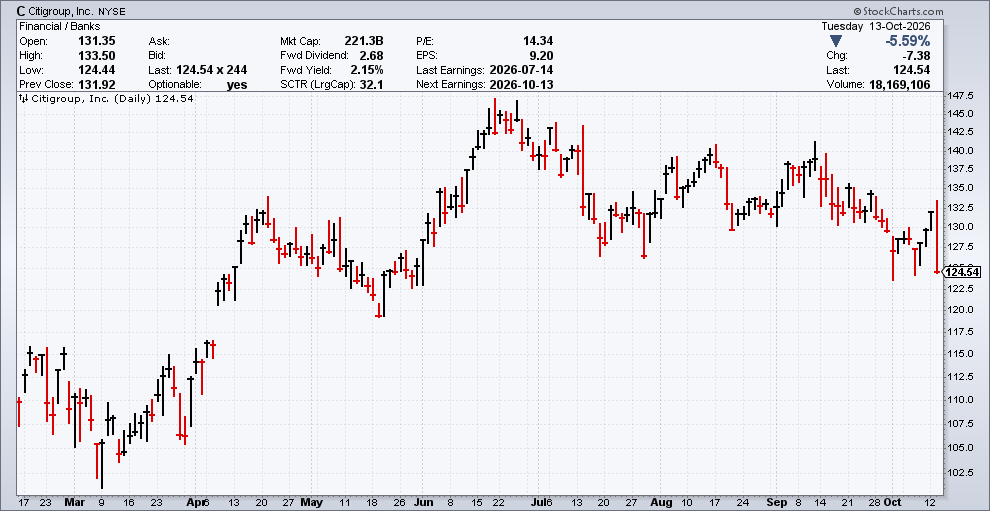
Citigroup (C) also beat the Street. Profits jumped 40% to $5.2 billion, or $2.85 per share versus consensus of $2.65 per share on revenue of $23.85 billion. Citi had strength in markets, banking, and services. CEO Jane Fraser has been working hard to make Citi more competitive, and her efforts appear to be paying off, but it’s still early. Citi has often been, in my opinion, too complex and too top-heavy. It’s less so today. The stock was down over 5% today.
Wells Fargo (WFC) had mixed results. Profit rose 6% to $5.95 billion, or $1.87 per share which was a slight beat, but revenue of $21.87 billion missed estimates. Net interest income and loan growth were positives, but revenue overall fell short. Shares declined about 3% today.
Outside of the banks, we had a nice report from UnitedHealth (UNH) today ($4.69 vs. $4.14). UNH also raised its full-year guidance to earnings of at least $20.50 per share. The stock popped 5% early this morning but gave back its gains.
Johnson & Johnson (JNJ) reported $2.59 per share, which was a beat by six cents. Sales were up 5.9% to $25.4 billion. J&J also raised its full-year guidance to earnings of at least $11.15 per share. The stock, which is a Dow component, dropped 5.7% today.
Domino’s Pizza (DPZ) made $4.60 per share which was a 27-cent beat. Management cut U.S. net store growth guidance. DPZ is -4.8% today.
Bank of America (BAC), Morgan Stanley (MS) and BlackRock (BLK) report tomorrow.
Higher Mortgage Rates Are Weighing on the Housing Sector
The WSJ notes that home sellers are “starting to blink” on prices. That’s hardly a surprise, and the problem isn’t exactly hiding. Higher mortgage rates, now over 7%, are impacting the entire housing market.
It won’t take long before the bond market’s problem becomes a housing industry problem. The number of homes for sale is nearly back to pre-pandemic levels. In September, housing inventory was only 5% below where it was seven years ago.
Until now, homebuilders only had one major concern: stubborn sellers. That meant that competition from the existing market was practically nil. Now that’s changing, and homebuilders are feeling the squeeze.
Major Homebuilders like Lennar and KB Home said they’re facing tough competition from regular owners who are more motivated to sell. Lennar said that homes sold in the western region are down $44,000 from a year ago.
In an effort to entice buyers, home sellers are slashing prices. As a result, the major homebuilders are following the market lower. If not, they’re missing out.
In the four weeks through Sept. 20, 21% of sellers in the existing-home market dropped their asking price, data from Redfin shows. The most significant activity is happening with concessions, which don’t show up in headline prices.
In August, 45% of home sellers gave concessions to buyers, such as offering to cover the closing costs or handing the buyer money for repairs. In oversupplied Sunbelt housing markets such as Atlanta and Nashville, Tenn., seven in 10 sellers are now offering concessions. These are the same markets where home builders tend to cluster.
We’ll soon see outright price cuts. What happened is that four years ago, mortgage rates started to rise, but people who locked-in low rates refused to budge. As a result, that starved the market for new supply.
The big homebuilders were able to keep selling homes because they offered big mortgage-rate buydowns which undercut the market rates. The problem is that those are expensive and they cut into profit margins.
The WSJ notes that some sales per community usually drop about 4% in September. This year, sales are down 18%.
Homebuilders appear to be walking into a price war with home sellers, and higher mortgage rates are making the outlook even worse.
That’s all for now. The CPI report is due out tomorrow morning. Wall Street expects a 0.6% jump in headline inflation and a 0.4% rise in core inflation. I’ll have more for you in the next issue of CWS Market Review.
– Eddy
Posted by Eddy Elfenbein on October 13th, 2026 at 6:14 pm
The information in this blog post represents my own opinions and does not contain a recommendation for any particular security or investment. I or my affiliates may hold positions or other interests in securities mentioned in the Blog, please see my Disclaimer page for my full disclaimer.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His