CWS Market Review – October 2, 2026
“I made my first investment at age eleven. I was wasting my life up until then. – Warren Buffett
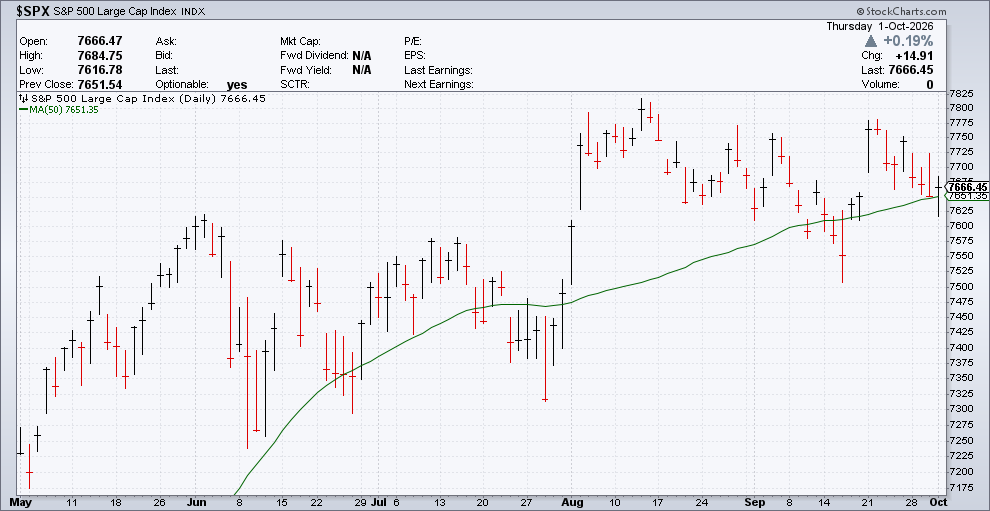
On Wednesday, the third quarter came to an end. Overall, Q3 was a decent quarter for Wall Street. The S&P 500 gained 2.03%. The Nasdaq was up 2.47%, and the Dow lost 2.70%. A gain of 3% for the quarter (before dividends) is not far from the long-term average for stocks.
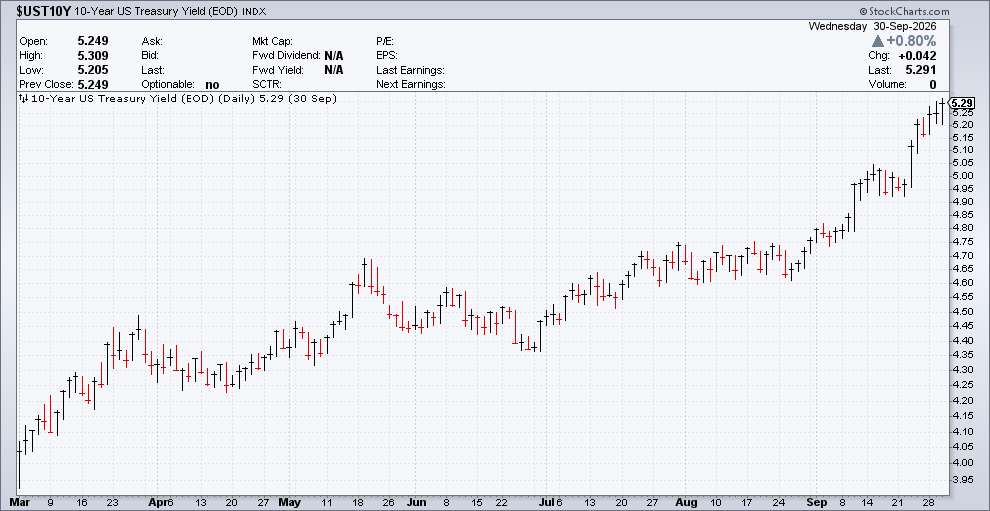
The real attention lately has been on the bond market. Yields continue to be high, and it appears that yield increases are themselves increasing. In February, the yield on the 19-year Treasury was just under 4%. Now it’s up to 5.26%, which was Wednesday’s closing yield.
This impacted just about anything you borrow money for (houses, cars, vacations). The average 30-year fixed-mortgage rate spiked to 7.28%.
In this week’s issue, I’ll discuss the outstanding earnings report from FactSet. The company beat expectations and offered optimistic guidance for next year. The stock has grown its earnings for the last 30 years in a row.
I’ll also go over the mess at FICO. I think Bill Pulte has it in for them. The stock got creamed this week.
I also have some Buy List updates for you, including two stocks that are starting to look like bargains.
The Economic Outlook Is a Mixed Bag
The big economic report this week is this morning’s jobs report. Before that were a couple of reports I wanted to highlight.
Headline PCE, which is the Fed’s preferred measure of inflation, rose by 0.3% last month. The core rate rose by 0.2%. That’s not bad.
Personal income rose 0.2%. Nominal consumer spending jumped 0.9%, and real spending rose 0.6%.
The third estimate for Q2 GDP growth was revised up to a 2.2% annualized rate, from 1.5% in the second estimate. Earlier quarters were also revised higher in the annual update.
The job-openings report (the JOLTS report) was little changed at 7.1 million. Hires were 5.2 million and separations 5.1 million. Layoffs were essentially flat. That is still a low-hire, low-fire economy.
ISM manufacturing was 54.5, essentially unchanged from 54.6 and slightly under consensus. This marks the ninth month of expansion. The Atlanta Fed’s GDPNow tracker stands at 3.7%.
Overall, this is a mixed picture for me. There are reasons for optimism, but those higher interest rates are not helping.
FactSet Beats Earnings and Raises Guidance
Before the opening bell on Wednesday, FactSet (FDS) reported its fiscal-Q4 earnings. This will be our final Buy List earnings report until earnings season starts up.
For the quarter, FactSet earned $4.52 per share. That’s up 11.6% over last year, and it beat the Street by 17 cents per share. For the whole year, FactSet made $18.01 per share. That’s an increase of 6.1%. FactSet’s full-year guidance had been for $17.25 to $17.75 per share.
Overall, it was a solid quarter for FDS. Organic revenues were up 7.1%, and organic ASV increased by 7% to $2,568.2 million. Annual ASV retention is above 95%. During Q4, average renewal-contract length increased by about 30%.
During Q4, FactSet returned more than $179 million to shareholders. That’s $138 million in buybacks and $41 million in dividends. During fiscal 2026, FactSet returned $808 million to shareholders and raised its dividend for the 27th year in a row.
CEO Sanoke Viswanathan said, “FactSet delivered strong results, highlighted by a record increase in organic ASV for both the fourth quarter and fiscal year with continued momentum across our AI and data solutions.”
For Q4, net cash provided by operating activities was $204.7 million, and free-cash flow was $177.3 million. This was the 30th consecutive year in a row that FactSet has increased its earnings, and revenues are up 47 years in a row.
For 2027, FactSet expects organic ASV to be up 5% to 6.5% and revenues to be between $2.6 and $2.625 billion. FactSet also expects earnings to be between $19.25 and $19.65 per share.
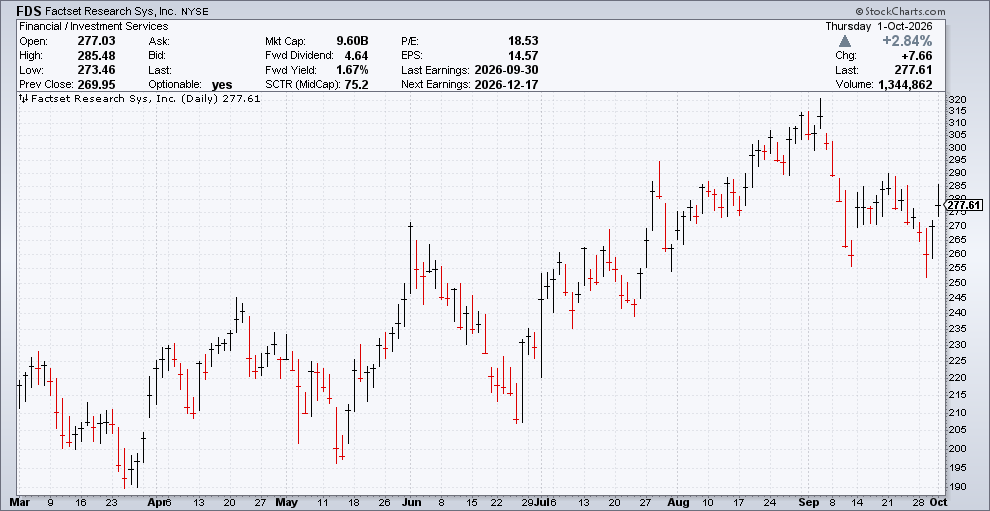
The stock rallied about 4% on Wednesday and another 3% on Thursday. FactSet remains a buy up to $300 per share.
Pulte Strikes Again
On Tuesday, shares of FICO (FICO) got creamed for a 26.5% loss. This came after the Federal Housing Finance Agency said that mortgage pricing will be simplified. This was FICO’s worst day since May 1989.
Bill Pulte, the director of the Federal Housing Finance Agency, said mortgage pricing will be simplified and that the new structure will incorporate VantageScore, a direct competitor to Fair Isaac’s FICO score.
The concern is that this will threaten FICO’s dominance. On Monday night, Pulte posted on social media that his agency would simplify mortgage pricing and that Fannie Mae and Freddie Mac are moving to a single pricing grid.
TransUnion said it would keep VantageScore 4.0 at $0.99 per pull through December 2028, well below typical FICO pricing. Rocket Mortgage had already moved to make VantageScore 4.0 its preferred model for eligible loans.
Pulte said that the new pricing grid structure will use VantageScore, which is a joint venture of the credit agencies. This means that potentially, people can bypass FICO. Pulte has been talking about this for a long time. The stock had a decent pushback rally on Thursday as investors reassessed how much pricing power FICO might actually lose. For now, I’m lowering our Buy Below on FICO to $800 per share.
Buy List Updates
I wanted to highlight two of our Buy List stocks this week that have fallen to attractive valuations. I enjoy watching high-quality stocks fall for transient or flimsy reasons.
The two stocks are Abbott Labs and Sprouts Farmers Market. Let’s start with Abbott Labs (ABT). This is a company that has increased its dividend every year for the last 54 years in a row.
Shares of Abbott improved for us over the summer, but it’s recently reversed course and fallen again.
In July, Abbott said that it made $1.31 for Q2. The company told us to expect $1.25 to $1.31 per share.
This was a solid quarter for Abbott. Q2 sales rose by 13.0% to $12.6 billion, and comparable-store sales rose by 4.8%. The best news is that Abbott increased its earnings guidance for this year.
Abbott had previously said it was expecting 2026 earnings to range between $5.38 and $5.58 per share. Now the company says it’s expecting earnings to fall between $5.45 and $5.60 per share. Wall Street had been expecting $5.48 per share. For all of 2026, Abbott projects comparable-sales growth of 6.5% to 7.5%. Barron’s said ABT had its best day in 24 years. Abbott is a buy up to $115 per share.
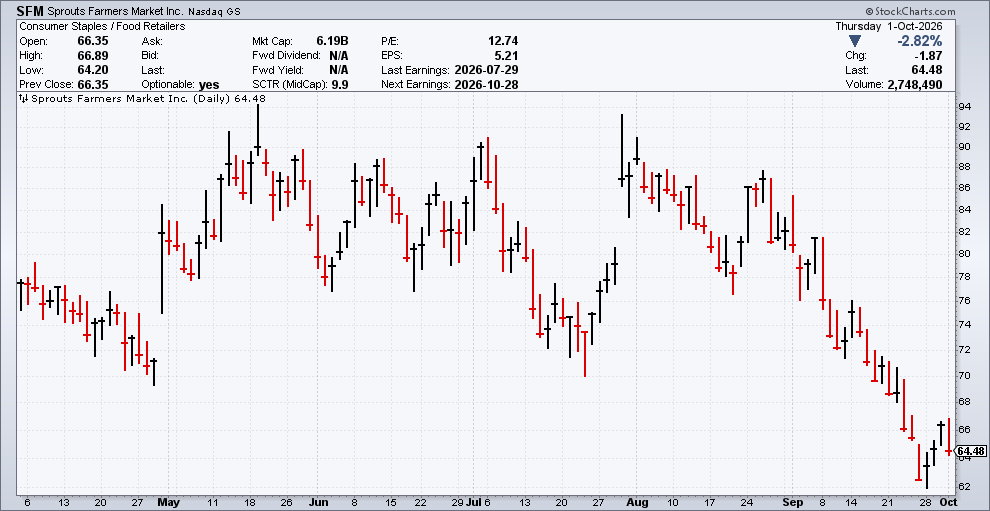
Sprouts Farmers Market (SFM) has also trended downward recently. The stock was downgraded by Deutsche Bank and some others. Sprouts also has a new CEO, which can be a concern for investors. The most pressing problem for Sprouts is weak comparable-store sales.
The good news is that Sprouts is steadily getting better. For Q2, SFM’s net sales were up 5% to $2.3 billion, and comparable-store sales were down 1%. That was expected.
Earnings came in at $1.37 per share, which was a three-cent beat. Sprouts now has 490 stores in 25 states. Sprouts ended the quarter with $224 million in cash and no balance on its credit facility.
For Q3, whose report is due out on October 28, Sprouts sees earnings between $1.20 and $1.24 per share and comparable-store sales between -0.5% and +1.5%. For the full year, SFM expects earnings of $5.32 to $5.40 per share and comparable-store sales of -0.5% to +0.5%. This week, I’m lowering our Buy Below price on Sprouts to $70 per share.
That’s all for now. The September jobs report is out later this morning. Wall Street expects to see a gain of 84,000 jobs. I’m also going to be paying attention to wage growth. Wall Street expects to see an increase of 0.3%. Frankly, this needs to improve. The consumer-credit report is due out on Wednesday, and the jobless-claims report is on Thursday. Tuesday October 13 is the unofficial start of earnings season. That’s when several of the major banks report results. I’ll have more market analysis for you in the next issue of CWS Market Review!
– Eddy
Posted by Eddy Elfenbein on October 2nd, 2026 at 7:12 am
The information in this blog post represents my own opinions and does not contain a recommendation for any particular security or investment. I or my affiliates may hold positions or other interests in securities mentioned in the Blog, please see my Disclaimer page for my full disclaimer.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His