CWS Market Review – October 27, 2026
(This is the free version of CWS Market Review. If you like what you see, then please sign up for the premium newsletter for $20 per month or $200 for the whole year. If you sign up today, you can see our two reports, “Your Handy Guide to Stock Orders” and “How Not to Get Screwed on Your Mortgage.”)
The Federal Reserve started its October meeting today. Tomorrow afternoon at 2 pm ET, the Fed will release its policy statement. I’ll spare you the suspense: the Fed won’t raise interest rates — at least not at this meeting — but a rate hike may be coming in a few weeks at the December meeting.
What about for next year? That’s hard to say right now, but I think it’s very possible that we’ll see two more rate hikes in 2027. Of course, a lot of that will depend on the economy and inflation.
The two-year Treasury, which is a good proxy for what the market wants, has settled around 4.75%. We’re doing a lot better than French bonds which are suffering through their worst decade since 1803.
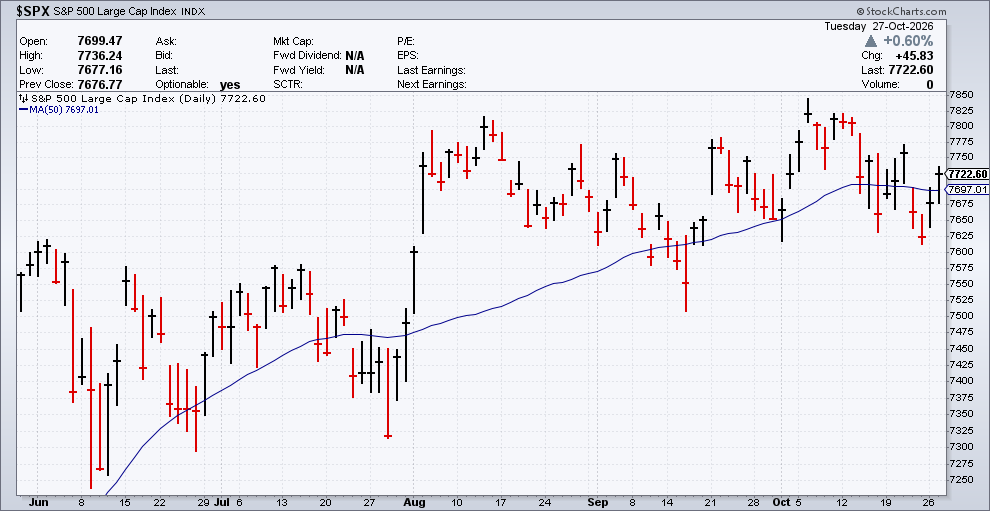
The stock market has suddenly gotten boring again. We had an exciting few days at the beginning of the month when the S&P 500 rallied 2.2% in four trading sessions to a new all-time high.
The big news this week was that Anthropic is filing for its IPO. Let’s take a closer look.
Anthropic to IPO in Massive Deal
Yesterday, Anthropic said that it’s going public, and Wall Street went absolutely ga-ga over the news — and Wall Street is a place that loves to go ga-ga over most anything. Folks have been waiting a long time for Anthropic to hit the market, and this deal will be massive. The news was enough to lift the entire tech sector.
Source: NYT
Anthropic is best known for Claude, its family of large language models. The company isn’t quite six years old, and it’s based in San Francisco. Anthropic plans to list on the Nasdaq under ticker symbol “ANT.”
As far as IPOs go, this will be one of the biggest of all time. The company was founded by the brother-sister team of Dario and Daniela Amodei. In 2021, Dario and a small group of researchers bolted from OpenAI to start Anthropic. OpenAI is now their big rival.
The consensus is that Anthropic will have a market value of $1.5 to $2 trillion. (When your margin of error is $500 billion, then you know you’re dealing with some very big numbers.) There are 15 companies with market caps over $1 trillion. Twelve are American. Zero are European.
Anthropic filed in June, but it gave the SEC some time to review all the details. The lead underwriters are Goldman Sachs and Morgan Stanley.
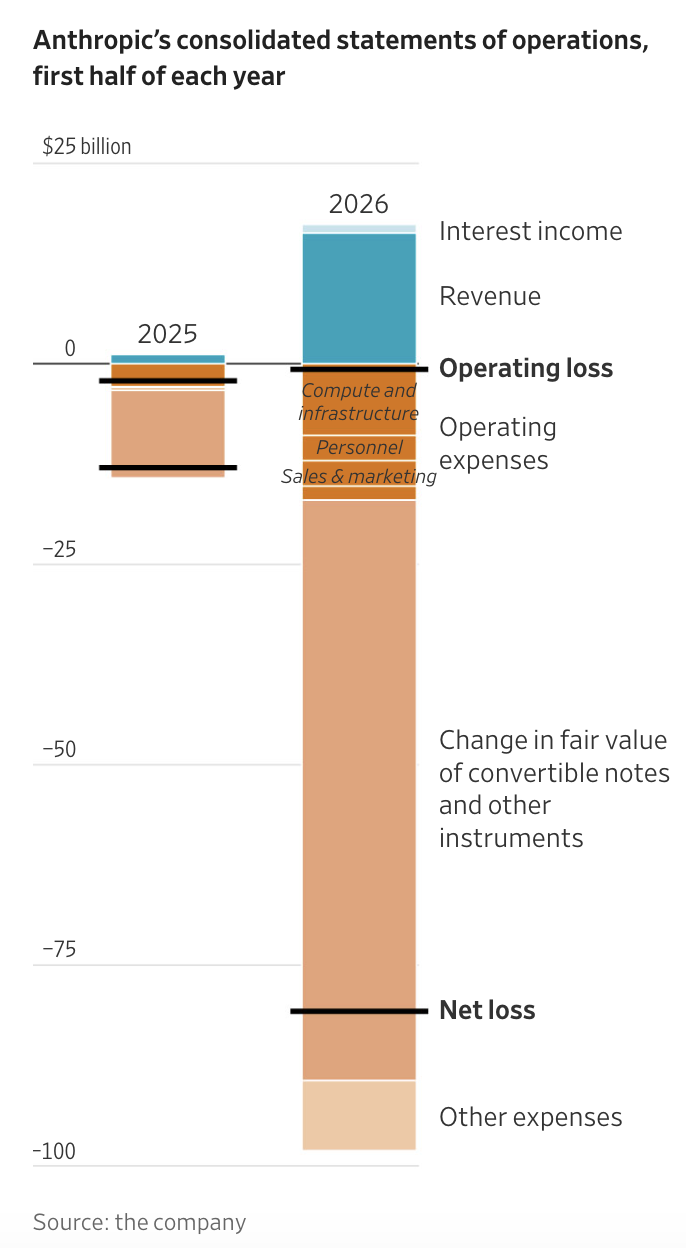
Anthropic is growing rapidly. For the first half of last year, they lost a measly $12.9 billion. For the first half of this year, Anthropic lost $80.7 billion. Now that’s some impressive growth.
Via: WSJ
For all last year, Anthropic lost $41.9 billion. In 2024, it had a loss of $8.3 billion. Anthropic said that as of June 30, it had $112.4 billion in cash and cash equivalents. International revenue made up for 27.8% of the company’s total revenue.
Interestingly, Anthropic’s customer base is far more diversified than those of other AI stocks. For example, Anthropic said that no single customer represents more than 10% of its revenue. Compare that with Nvidia which has five clients with more than 10% of its revenues.
Anthropic said it will use the funds from its IPO for general corporate expenses. The company also said that it may use the money to buy out other firms, which I almost certainly expect. The benefit of an elevated share price is that it can be used as cheap currency to buy out your rivals.
Anthropic is a classic “asset-light” company, meaning it doesn’t own much of anything. Instead, it leases what it needs. Anthropic currently has just over $1 billion in property and equipment. That includes $432 million of net property and equipment associated with finance leases. At the end of 2025, Anthropic’s future undiscounted lease obligations were just $50.2 billion. Now that’s at $321 billion.
Anthropic has an unusual corporate structure. Founder LLC owns 50.1% of the stock. The LLC has just seven members: Dario and Daniela Amodei, plus five other executives.
At the end of Q3, Anthropic said it had 5,300 employees. That works out to $6.6 million in revenue per employee. Anthropic said that internally it refers to its employees as Ants. I’m not sure what to think of that.
Anthropic said it will pay SpaceX around $3.1 billion per month to “access compute powered by NVIDIA GPUs.” SpaceX said in its Q3 report that Anthropic paid them $5 billion which is more than one-third of its total revenue. In its prospectus, Anthropic only named two competitors, OpenAI and Google.
The company listed 90 pages of risk factors. There’s been a backlash against data centers across the county. A few states and cities have passed moratoriums on new data center construction, and many more are considering the idea. Anthropic listed as a business risk having so much of its chipmaking done in Taiwan, especially at Taiwan Semi.
After the IPO, Google will have the option to become a very significant shareholder of Anthropic. In March, Anthropic agreed to give Google an option to buy up to $10 billion worth of shares in a private placement.
Amazon also has had a very close relationship with Anthropic. Since 2023, Amazon has invested $13 billion in Anthropic, and it may invest $20 billion more. Amazon owns convertible notes that could be worth $1.84 billion once Anthropic IPOs.
I’m not going to be an investor in Anthropic’s IPO, but I will be watching it closely. I expect to see them use their cash infusion to buy out a lot of competitors.
Hawkins Inc. Soars on Earnings
If you’ve been following me for a while, you’ll know that I’m a big fan of little-known stocks that are great businesses even though they’re not followed by any analyst on Wall Street (in other words, the exact opposite of Anthropic). A great example is little Hawkins Inc. (HWKN) of Roseville, Minnesota. Hawkins is one of those small- to mid-cap industrial stocks that I love. It has a market value of $3 billion.
The company describes itself as “a leading specialty chemical and ingredients company.” Snoresville, right? No, Hawkins isn’t the most exciting business, but it’s an important one, and it’s something people need. Hawkins “formulates, distributes, blends, and manufactures products for its Industrial, Water Treatment, and Health & Nutrition customers.”
I first told you about Hawkins in June 2024. Since then, it’s up over 72%. Hawkins has been around since 1938. The company has 64 facilities across 28 states. Hawkins has about 1,200 employees and last year, it generated revenue of $1 billion.
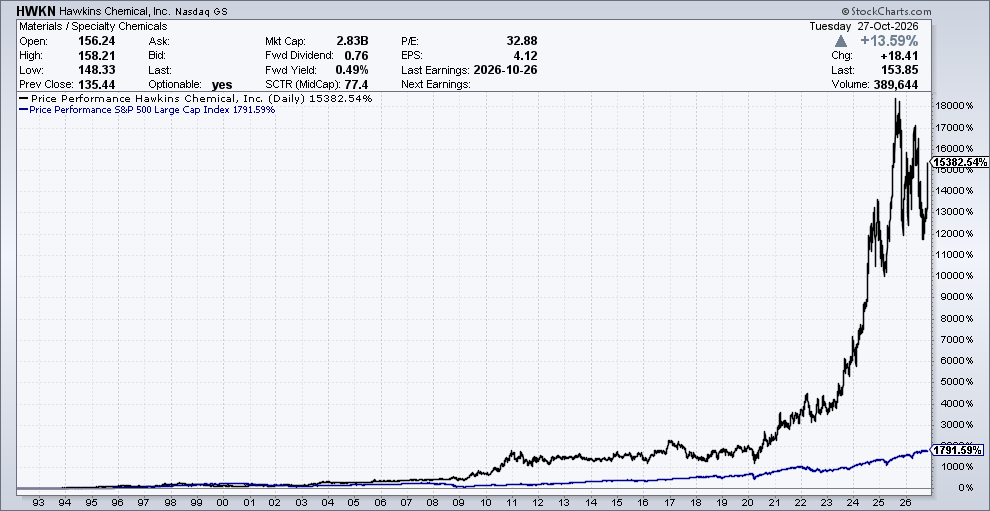
Now for the best part. Since 1992, Hawkins is up by more than 150-fold. The S&P 500 (in blue) looks like a flat line in comparison. Hawkins has also raised its dividend consistently for nearly 40 years.
Hawkins used to have a practice of announcing 10% or 15% stock dividends each year. These tended to be in line with the stock’s long-term performance. As a result, the nominal share price didn’t move much. That might you lead you to believe that the stock hasn’t done well, but it’s been a huge winner. Despite all its success, still only two Wall Street analysts bother following Hawkins.
After yesterday’s closing bell, Hawkins released another good earnings report. For its fiscal Q2, which ended on September 27, Hawkins had sales growth of 12%, and earnings were up 23% to $1.34 per share. I can’t say whether that beat earnings since there is no consensus. The average of the two analysts was for $1.18 per share.
The market loved the earnings report. At one point, Hawkins was upv17% today before settling for a gain of 13.6% today. This was a great bargain hiding in plain sight.
That’s all for now. The Fed will release its policy statement tomorrow at 2 pm ET. Don’t expect any rate increase for now. I’ll have more for you in the next issue of CWS Market Review.
– Eddy
Posted by Eddy Elfenbein on October 27th, 2026 at 7:06 pm
The information in this blog post represents my own opinions and does not contain a recommendation for any particular security or investment. I or my affiliates may hold positions or other interests in securities mentioned in the Blog, please see my Disclaimer page for my full disclaimer.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His