-
Carney Defends Capitalism
Posted by Eddy Elfenbein on July 15th, 2009 at 1:32 pmJohn is spot on. CIT really made a mistake in not failing earlier and more massively. Oh well.
-
Lap Dances Apparently Not Hurt By Recession
Posted by Eddy Elfenbein on July 15th, 2009 at 12:06 pmGuess what strip club stock is 200% in the last four months?
Rick’s Cabaret International (RICK)
Special bonus! Hear Erin Burnett make a reference to Mark Haines’ ass. It’s not business, it’s CNBC.
-
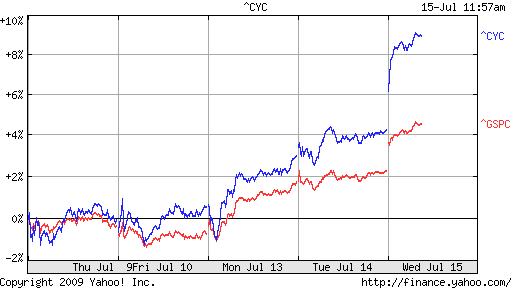
Today’s Rally Is Led by the Cyclicals
Posted by Eddy Elfenbein on July 15th, 2009 at 11:57 amIt’s all about the cyclicals:
-
The Puzzling Equity Premium Puzzle
Posted by Eddy Elfenbein on July 15th, 2009 at 10:28 amDavid Merkel has some interesting thoughts on the Equity Premium Puzzle.
My so-far-ignored-by-the-Noble committee idea is that there is and should be an premium for equities, but it shouldn’t be very much. The idea is simple: If you lend a company money, both you and the company implicitly agree that they can do better with it than you. Therefore, their ROE ought to top the interest rate on the loan.
A bond can’t buy a stock, but a stock can buy a bond. Moreover, a stock can use leverage to buy even more bonds. Therefore the size of the equity premium ought to be related to the size of the yield curve. What exactly the relationship is…well, I haven’t worked that part out yet. -
Stat of the Day
Posted by Eddy Elfenbein on July 14th, 2009 at 3:41 pmGeneral Motors, days in bankruptcy = 39
Jesus, days in wilderness = 40
(Source: Bloomberg, KJV) -
Daniel Gross: The Recession is Over (Sorta)
Posted by Eddy Elfenbein on July 14th, 2009 at 3:13 pmAt the new-and-improved Newsweek, Daniel Gross hops on the Dennis Kneale bandwagon and declares the recession over — though he has a far more intelligent and sardonic analysis:
(T)wo of the best and most objective forecasters, who are not connected to investment banks or to the CNBC noise machine, have recently called the upturn. Macroeconomic Advisers, the St. Louis-based consulting firm that compiles a monthly GDP index, reported to its clients Monday that while second-quarter GDP was tracking at negative 0.1 percent (recession), the third quarter was tracking at 2.4 percent growth.
The folks at the Economic Cycles Research Institute agree enthusiastically. It’s not because they’ve detected green pea shoots in Central Park. Rather, it’s because we’ve seen the three P’s, says Laskhman Achuthan, managing director at ECRI, which has been studying business cycles for decades and was one of the few outfits to call the last two recessions with any degree of accuracy.
The economic data that get the most play in the news—unemployment, retail sales—are coincident or lagging indicators and historically have not revealed much about directional changes in the economy. ECRI’s proprietary methodology breaks down indicators into a long-leading index, a weekly leading index, and a short-leading index. “We watch for turning points in the leading indexes to anticipate turning points in the business cycle and the overall economy,” says Achuthan. It’s tough to recognize transitions objectively “because so often our hopes and fears can get in the way.” To prevent exuberance and despair from clouding vision, ECRI looks for the three P’s: a pronounced rise in the leading indicators; one that persists for at least three months; and one that’s pervasive, meaning a majority of indicators are moving in the same direction.
The long-leading index—which goes back to the 1920s and doesn’t include stock prices but does include measures related to credit, housing, productivity, and profits—hits bottom and starts to climb about six months before a recession ends. The weekly leading index calls directional shifts about three to four months in advance. And the short-leading index, which includes stock prices and jobless claims, is typically the last to turn up.
All three are now flashing green. According to Achuthan, the long-leading index growth rate has been recovering since November 2008, the weekly leading index has been recovering since last December, and the short-leading index growth rate bottomed in February 2009. In sequence, each turned up, “and by April the three Ps had all been satisfied.” Sure, corporate profits continue to disappoint, and the unemployment rate is climbing. But for ECRI, which navigates by relying exclusively on its instruments, that’s only a part of their picture. They’re the Spocks of the economic forecasting crowd—unemotional, uninvested in anything but the logic of what history and their dashboard tell them. “From our vantage point, every week and every month our call is getting stronger, not weaker, including over the last few weeks,” says Achuthan. “The recession is ending somewhere this summer.” In fact, it may already be over.Hmmm…I hope he’s right but hope isn’t a good research tool. The fact is that the economy still faces a number of headwinds, the most crucial is the deleveraging that’s going on. My fear is that we’re in for a prolonged period of sluggish growth.
-
Goldmine $achs
Posted by Eddy Elfenbein on July 14th, 2009 at 10:02 am
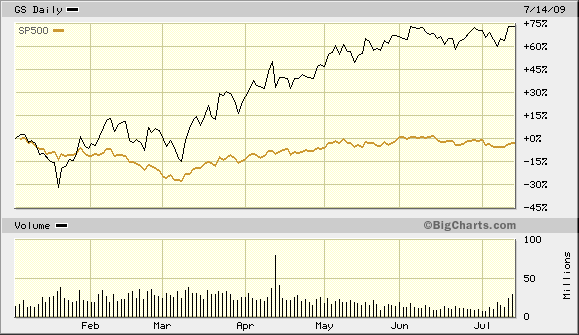
When J.P. Morgan formed U.S. Steel in 1901, Henry Adams said that he was “apparently trying to swallow the sun.” Now it looks like Goldman Sachs has swallowed the galaxy.
Goldman’s second-quarter earnings report was staggering. From April through June, Goldman earned $3.44 billion. That works out to $4.93 a share which is head and shoulders above Wall Street’s consensus of $3.53.Chief Executive Officer Lloyd Blankfein made Goldman Sachs the highest-paying Wall Street firm in history before last year’s credit freeze led him to convert to a bank, accept government funds and report the first quarterly loss as a public company. This year Goldman Sachs has issued new stock, repaid the U.S. Treasury and reaped fees from selling stocks and bonds.
“Goldman’s got a sweet spot in here, they were the go-to players,” said Peter Sorrentino, a senior portfolio manager at Huntington Asset Advisors in Cincinnati, which oversees $13.8 billion including Goldman shares, before earnings were released. “For the time being, they’ve got kind of an open playing field all to themselves.”The stock is down slightly this morning, but that’s following its big day yesterday.
-
BusinessWeek Could Be Sold for $1
Posted by Eddy Elfenbein on July 14th, 2009 at 9:54 amFrom the FT:
McGraw-Hill could reap just $1 from a sale of Business Week, according to people familiar with the 80-year-old financial magazine’s losses.
The publisher has appointed Evercore, the boutique investment bank, to sell the business after concluding it was non-core, two people familiar with the decision said.
McGraw-Hill, which owns the Standard & Poor’s rating agency and a large educational publisher, would only say it was “exploring strategic options” for Business Week. Evercore did not return calls.(Via: Ritholtz)
-
Will Someone PLEASE Pay Attention to Me?
Posted by Eddy Elfenbein on July 14th, 2009 at 12:52 am -
Sorry Folks, the Fed is NOT a Private Bank
Posted by Eddy Elfenbein on July 13th, 2009 at 1:09 pmI’m afraid that I don’t know exactly who Spencer Pratt and Heidi Montag are. I gather they’re celebrities of some sort, but perhaps not truly authentic celebrities.
In any event, what brought them to my attention was Mr. Pratt’s recent commentary on the Federal Reserve on Alex Jones’ InfoWars. Jones is someone I am familiar with; he uses his show to warn Americans of the growing danger posed by the New World Order.
The NWO is apparently a conspiracy so vast and complex that it actually reaches into the depths of human understanding of reason and logic to cruelly twist all of Mr. Jones’ arguments into errant nonsense.
If you jump to the eight minute mark you can hear Spencer tell us that the Federal Reserve is a private company just like Federal Express.
This seems to be a popular misconception about the Federal Reserve. Like many things said about the Fed, it’s not true—the Fed is not a private bank. The best way to describe it would be a hybrid quasi public system. Not surprisingly, the end result was part of a political compromise. If my business were run that way, I wouldn’t consider it private.
The members of the Fed’s board are appointing by the President and are confirmed by Congress. The FOMC, which is the policy committee, is mixed with board members and regional bank presidents.
The regional reserve banks do issue stock to member banks but it’s very different from owning shares in FedEx. For one, the banks can’t sell or trade the stock. The dividends are set at 6% a year. Everything after that goes to the Treasury. Plus, the banks have to invest 3% of their capital in the Fed.
Incidentally, FedEx’s CEO is Fred Smith who’s a member of Skull and Bones so perhaps it too is part of the New World Order.
(HT: LOLfed)
-
Archives
- November 2026
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His