-
Oracle’s Q2 Guidance
Posted by Eddy Elfenbein on September 17th, 2015 at 10:22 amFrom the conference call:
I am going to give you constant currency guidance, but if exchange rates remain the same as they are right now, we expect to see a currency headwind of about 6% on revenue and $0.05 on earnings per share. But again, it could be significantly worse. Maybe if we are lucky, it could be a little bit better. All of my guidance today is on a non-GAAP basis and in constant currency. So, here it goes.
SaaS and PaaS revenue is expected to grow 36% to 40%. Cloud IaaS revenue is expected to grow 5% to 9%. Total cloud and on-premise software is expected to grow from 0% to 2%. Total revenue is expected to range from a negative 2% to a positive 1%. Non-GAAP EPS in constant currency is expected to be somewhere between $0.63 and $0.66. Now, this assumes a non-GAAP tax rate of 25.5%. Of course, if this quarter is any example, it may end up being different. Looking further out, we expect to see a material acceleration in SaaS and PaaS revenue. As a result, I am providing full fiscal year guidance for some key items. As before, my guidance on the full year is in constant currency.
SaaS and PaaS revenue is expected to grow around 50%. On-premise software is expected to grow approximately 1%. Total cloud and on-premise software is expected to grow between 3% and 4%. Finally, SaaS and PaaS gross margins are expected to materially improve in the second half and exit the year at around 60%.
-
Morning News: September 17, 2015
Posted by Eddy Elfenbein on September 17th, 2015 at 6:29 amChina, U.S. Reach Agreement on High-Speed Rail Before Xi Visit
Swiss Central Bank Leaves Interest Rates Unchanged
BOJ Governor Kuroda Comments at News Conference
Silent on Priorities, Yellen Makes Fed Choice a Cliffhanger
Health Care Gains, But Income Remains Stagnant, the White House Reports
U.S. Home-Builder Confidence Climbs in September, Industry Group Says
It’s Time To Get Serious About Reducing Food Waste, Feds Say
GM Said to Settle Criminal Case Over Ignition Switches
Expedia-Orbitz Deal Gains Antitrust Clearance
AB InBev, SABMiller Deal Expected to Face Global Antitrust Grilling
Oracle’s Revenue Misses Estimates as License Sales Decline
U.S. Judge Certifies Class Action Over Target Corp Data Breach
Roger Nusbaum: Learning From Target Date Funds Without Actually Using Them
Cullen Roche: Three Things I Think I Think – Stupid Markets Edition
Be sure to follow me on Twitter.
-
Oracle Earns 53 Cents per Share
Posted by Eddy Elfenbein on September 16th, 2015 at 4:39 pmAfter the closing bell, Oracle (ORCL) reported fiscal Q1 earnings of 53 cents per share which was one penny ahead of expectations. Once again, the strong dollar was a big factor. Total revenues fell 2% to $8.4 billion but rose by 7% in constant currency. Oracle earned 62 cents per share in last year’s Q1.
“Our traditional on-premise software business plus our new cloud business grew at a combined rate of 6% in constant currency,” said Oracle CEO, Safra Catz. “This growth is being driven by new SaaS and PaaS annual recurring cloud subscription contracts which almost tripled in the quarter. As our cloud business scales-up, we plan to double our SaaS and PaaS cloud margins over the next two years — starting from 40% this just completed Q1, to approximately 60% this coming Q4, and then on up to 80% two years from now. Rapidly growing cloud revenue combined with a doubling of cloud margins will have a huge impact on EPS growth going forward.”
“In Q1 SaaS and PaaS revenue was up 38% in constant currency — in Q4 that revenue growth rate will be over 60%,” said Oracle CEO, Mark Hurd. “That cloud revenue growth rate is being driven by a year-over-year bookings growth rate of over 150% in Q1. Our increasing revenue growth rate is in sharp contrast to our primary cloud competitor’s revenue growth rates which are on their way down.”
“We are still on target to book between $1.5 and $2.0 billion of new SaaS and PaaS business this fiscal year,” said Oracle Executive Chairman and CTO Larry Ellison. “That means Oracle would sell between 50% more and double the amount of new cloud business than salesforce.com plans to sell in their current fiscal year. Oracle is the world’s second largest SaaS and PaaS company, but we are rapidly closing in on number one.”
-
Microsoft Boosts Dividend by 16%
Posted by Eddy Elfenbein on September 16th, 2015 at 12:44 pmI recently said I expected Microsoft (MSFT) to raise their quarterly dividend. It was at 31 cents per share, and I was expecting an increase to 34 cents per share. The board outdid me! They raised it to 36 cents per share. That’s a 16% increase. Microsoft now pays out $1.44 per share per year. Going by yesterday’s close, MSFT yields 3.3%.
If you bought Microsoft on July 25, 1991 at $66 per share, adjusting for stock splits totaling 48-for-1, then your cost basis is $1.375 per share. That means your dividend is now over 100% based on your purchase price.
-
Weak CPI Report for August
Posted by Eddy Elfenbein on September 16th, 2015 at 10:20 amThe inflation report for August came out this morning. Headline inflation fell 0.071% last month. So we’re talking about raising interest rates while we’re experiencing deflation. Year-over-year inflation rose from 0.17% through July to 0.20% through August.
It’s not just commodity prices. Core inflation rose by just 0.074%. That’s the lowest rate all year. Core inflation is now running at just over 2% this year.
Here’s the year-over-year inflation rate (black) along with the Fed funds rate (blue). You can see that the Fed has kept real rates negative (black higher than blue), but that’s come undone recently. In other words, by doing nothing, the Fed has effectively tightened rates.
-
High Quality Wins
Posted by Eddy Elfenbein on September 16th, 2015 at 9:40 amFrom Business Insider:
Investing in the stock market may be easier than we think, according to Chris Montagu and the equities research team at Citi.
They have identified that the strategy of investing in so-called high-quality stocks has returned 5% to 7% a year on average since 1995.
All you have to do is pick out big, boring stocks with decent profit margins, low debt, and reliable income flows.
Then sit back and wait.
-
The Dividend Bull Market
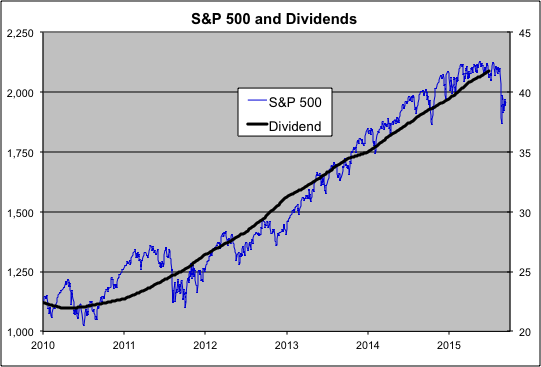
Posted by Eddy Elfenbein on September 16th, 2015 at 9:32 amHere’s a look at the S&P 500 (blue line, left scale) along with its trailing dividends (black line, right scale). The two lines are scaled at a ratio of 50-to-1. That means that whenever the lines cross, the market’s dividend yield is exactly 2%.
What’s striking is that dividends have risen right along with prices. Or perhaps, vice versa. I would hardly say that the market’s dividend yield is the end-all in valuations, but the persistence of 2% is noteworthy.
Only recently has it broken down. Through June, the S&P 500 had paid out $41.74 in dividends for the previous four quarters. (That’s the index-adjusted number.) Companies are still churning out the dividend increases. Viewed from this perspective, the market is hardly a bubble. What I like about dividend analysis is how stable dividends are.
I estimate that the trailing four-quarter dividend number will be $42.65 at the end of this month. To be yielding 2%, the S&P 500 would then need to be at 2,132.50 which would be a new closing high.
-
18 Years Ago Today, Steve Jobs Returns
Posted by Eddy Elfenbein on September 16th, 2015 at 8:43 amEighteen years ago today, Steve Jobs returned to Apple (AAPL), the company he founded. The stock closed that day, September 16, 1997, at $21.94 per share. Adjusted for two 2-for-1 and one 7-for-1 splits, Apple was trading at 78.3 cents per share in today’s terms. The high from this past spring was $134.54. The company is currently worth two-thirds of a trillion dollars.
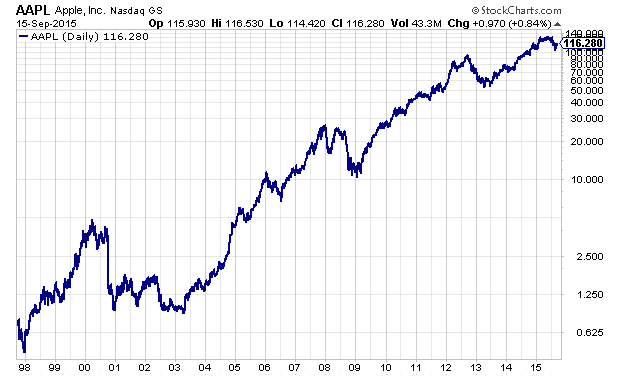
Interestingly, the stock was not an immediate hit when Jobs came back. Within a few days, it dropped down to $12.75 per share, or about 45.5 cents adjusted for splits. That was barely above Apple’s IPO price from 17 years before.
(Apple IPO’d at $22 per share; adjusted for splits of 56-for-1, that comes to 39.3 cents in today’s dollars. The IPO was the largest offering since Ford in 1956.)
At its low point in 2003, Apple was lower than where it had been in 1983. Think about that! Twenty years of no gain, and this was well after Steve Jobs had returned.
Apple’s single-worst day came on September 29, 2000 when the stock plunged 51.9%. The catalyst was that Apple said they were going to miss earnings. That was also Apple’s highest volume day. It traded over 1.8 billion shares that day.
Apple has suffered other big drops. On the day of the 1987 crash, Apple fell 24.4%. The stock has fallen more than 10% in a single day 26 times, which is nearly once per year.
Apple’s single-best day came on August 6, 1997 when it soared 33.2%. That was the day Steve Jobs, who was then an advisor to Apple, announced at a MacWorld trade show that Microsoft was investing $150 million in Apple preferred stock. That moved saved Apple. At the time, people in the crowd booed. Here’s the video:
Jobs had left Apple 30 years ago this Friday, September 18, 1985. At the time, the stock was at $16.25 per share, or 29 cents adjusted for splits. So in the 12 years of his absence, Apple had gone from 29 cents to 78 cents. That was a gain of 170%, which works out to 8.6% annually.
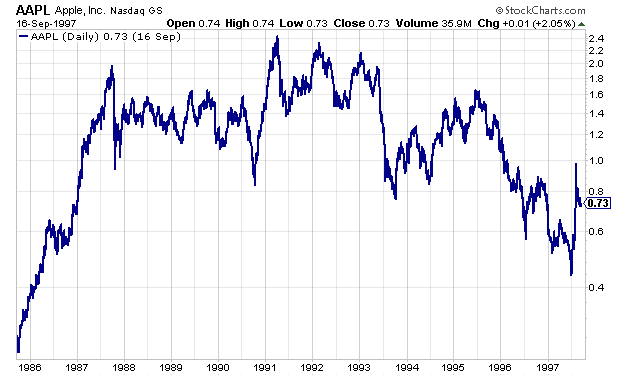
In the last 18 years, the stock is up nearly 150-fold, or 32% annually.
-
Morning News: September 16, 2015
Posted by Eddy Elfenbein on September 16th, 2015 at 7:07 amEurozone Inflation Slows Unexpectedly in August
Standard & Poor’s Downgrades Japan’s Sovereign Credit Rating From AA- to A+
Emerging Stocks Rally With Currencies Before Fed as China Jumps
OECD Trims Growth Outlook But Urges Fed Action This Week
Finance Replaces OPEC as Oil Supply Arbiter
Volatility Seen Lingering No Matter What the Fed Does
U.S. Retail Sales Rise 0.2%, as Consumers Show More Confidence
Anheuser-Busch InBev Approaches SABMiller on Possible Takeover
HP to Cut Up to 30,000 More Jobs in Enterprise Business
Motorola Solutions Moving Headquarters, 800 Jobs to Chicago
Comcast Creates New Enterprise Services Unit to Target Big Businesses
Microsoft Is Undervalued Ahead Of Dividend Raise
FedEx Trims 2016 Forecast as First-Quarter Earnings Fall Short
Jeff Carter: Consumer Jumps Into B2B: B2B Jumps Into Consumer
Howard Lindzon: Twitter a Buy?
Be sure to follow me on Twitter.
-
The S&P 500 and its Earnings
Posted by Eddy Elfenbein on September 15th, 2015 at 1:25 pmHere’s an updated look at the S&P 500 and its earnings line. The index is the black line and it follows the left scale. The earnings line is yellow and it follows the right. The future part of the yellow line is based on Wall Street’s consensus.
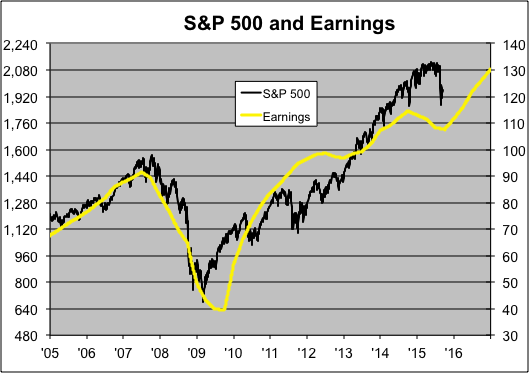
The two lines are scaled at a ratio of 16-to-1 so whenever the lines cross, the market’s P/E Ratio is exactly 16. I don’t mean to imply that’s fair value. The graph simply works best at that ratio.
-
Archives
- November 2026
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His