-
Q3 GDP +3.5%
Posted by Eddy Elfenbein on October 30th, 2014 at 8:45 amThe government just reported that the economy grew, in real terms, by 3.5% last quarter. That’s a decent number. Four of the last five quarters have shown good growth, although there’s obviously room for improvement. Nominal GDP rose by 4.87% last quarter.
With the end of the third quarter, it’s also the end of the government’s fiscal year. That means that we have one more data point for the government’s taxing, spending and deficit.
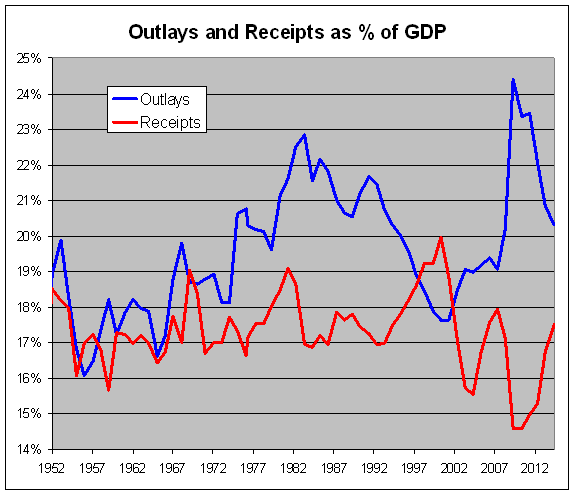
For 2014, outlays were 20.32% of GDP. Receipts were 17.52%. Here’s a look at the historical data.
The deficit was 2.82%.
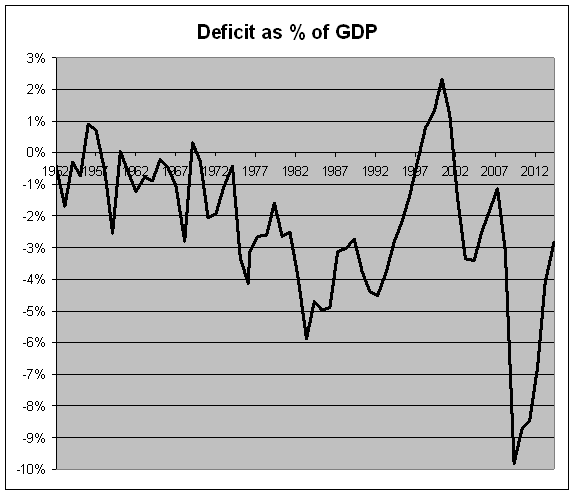
The recent deficits were ugly, but it’s improved a lot. Last year’s deficit was lower than every year except one between 1982 and 1994.
This is unusual, but the numbers for FY 2014 were almost the exact same as those for FY 1994. Receipts were 20.31% in 1994 and 20.32% in 2014. Outlays were 17.49% in 1994 and 17.52% in 2014. The deficit was the same, 2.82% in both years.
-
Morning News: October 30, 2014
Posted by Eddy Elfenbein on October 30th, 2014 at 7:07 amEuropean Investors Get Jittery Over Banking Stocks
German Jobless Total Falls in October
Fed Ends QE, Perks Up Labor Market Outlook
Fed’s Lonesome Dove Dissents as Brighter Outlook Appeases Hawks
Time Warner Cable Profit Drops as Subscriptions Wane
Shell Profit Increases as Refining Trumps Lower Oil Prices
Lufthansa Lowers 2015 Earnings Outlook
Volkswagen Q3 Profits Jump 56%
Bayer Q3 Adj Profit Gains Slightly on Strong Crop Chemicals
’Dragon’ Sequel Sends Dreamworks Revenue Soaring; Shares Rise
Visa Posts Lower 4Q Profit; Beats Street Views
Kraft Profit Drops on Higher Commodity Costs
Food’s Latest Scandal: What’s Wrong With Your Shrimp
Joshua Brown: 20 Key Takeaways from Stocktoberfest 2014
Jeff Carter: Prediction Markets
Be sure to follow me on Twitter.
-
The Best Time of the Year to Invest
Posted by Eddy Elfenbein on October 29th, 2014 at 4:41 pmToday is October 29 which has historically marked the end of the worst period of the year for stocks. I took the Dow’s entire history and found that the index averages a gain of just 0.34% from May 6 to October 29 (“sell in May and go away”).
But from October 29 to May 6, the Dow has averaged a gain of 7.00%. This means that nearly 95% of the Dow’s average annual gain has come in slightly less than half the year. The rest of the other time, the market is basically flat.
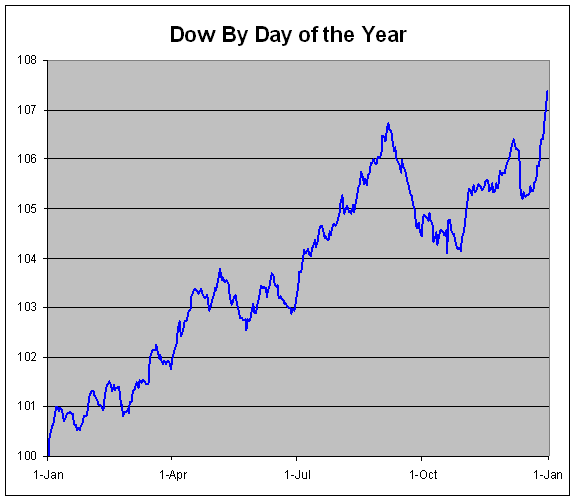
I don’t think this data should be used to make any investment decisions. I simply think it’s interesting to see what the market has done historically.
-
RIP: QE
Posted by Eddy Elfenbein on October 29th, 2014 at 2:05 pmThe Fed announces the end of Quantitative Easing:
Information received since the Federal Open Market Committee met in September suggests that economic activity is expanding at a moderate pace. Labor market conditions improved somewhat further, with solid job gains and a lower unemployment rate. On balance, a range of labor market indicators suggests that underutilization of labor resources is gradually diminishing. Household spending is rising moderately and business fixed investment is advancing, while the recovery in the housing sector remains slow. Inflation has continued to run below the Committee’s longer-run objective. Market-based measures of inflation compensation have declined somewhat; survey-based measures of longer-term inflation expectations have remained stable.
Consistent with its statutory mandate, the Committee seeks to foster maximum employment and price stability. The Committee expects that, with appropriate policy accommodation, economic activity will expand at a moderate pace, with labor market indicators and inflation moving toward levels the Committee judges consistent with its dual mandate. The Committee sees the risks to the outlook for economic activity and the labor market as nearly balanced. Although inflation in the near term will likely be held down by lower energy prices and other factors, the Committee judges that the likelihood of inflation running persistently below 2 percent has diminished somewhat since early this year.
The Committee judges that there has been a substantial improvement in the outlook for the labor market since the inception of its current asset purchase program. Moreover, the Committee continues to see sufficient underlying strength in the broader economy to support ongoing progress toward maximum employment in a context of price stability. Accordingly, the Committee decided to conclude its asset purchase program this month. The Committee is maintaining its existing policy of reinvesting principal payments from its holdings of agency debt and agency mortgage-backed securities in agency mortgage-backed securities and of rolling over maturing Treasury securities at auction. This policy, by keeping the Committee’s holdings of longer-term securities at sizable levels, should help maintain accommodative financial conditions.
To support continued progress toward maximum employment and price stability, the Committee today reaffirmed its view that the current 0 to 1/4 percent target range for the federal funds rate remains appropriate. In determining how long to maintain this target range, the Committee will assess progress–both realized and expected–toward its objectives of maximum employment and 2 percent inflation. This assessment will take into account a wide range of information, including measures of labor market conditions, indicators of inflation pressures and inflation expectations, and readings on financial developments. The Committee anticipates, based on its current assessment, that it likely will be appropriate to maintain the 0 to 1/4 percent target range for the federal funds rate for a considerable time following the end of its asset purchase program this month, especially if projected inflation continues to run below the Committee’s 2 percent longer-run goal, and provided that longer-term inflation expectations remain well anchored. However, if incoming information indicates faster progress toward the Committee’s employment and inflation objectives than the Committee now expects, then increases in the target range for the federal funds rate are likely to occur sooner than currently anticipated. Conversely, if progress proves slower than expected, then increases in the target range are likely to occur later than currently anticipated.
When the Committee decides to begin to remove policy accommodation, it will take a balanced approach consistent with its longer-run goals of maximum employment and inflation of 2 percent. The Committee currently anticipates that, even after employment and inflation are near mandate-consistent levels, economic conditions may, for some time, warrant keeping the target federal funds rate below levels the Committee views as normal in the longer run.
Voting for the FOMC monetary policy action were: Janet L. Yellen, Chair; William C. Dudley, Vice Chairman; Lael Brainard; Stanley Fischer; Richard W. Fisher; Loretta J. Mester; Charles I. Plosser; Jerome H. Powell; and Daniel K. Tarullo. Voting against the action was Narayana Kocherlakota, who believed that, in light of continued sluggishness in the inflation outlook and the recent slide in market-based measures of longer-term inflation expectations, the Committee should commit to keeping the current target range for the federal funds rate at least until the one-to-two-year ahead inflation outlook has returned to 2 percent and should continue the asset purchase program at its current level.
-
Three Buy List Earnings Reports
Posted by Eddy Elfenbein on October 29th, 2014 at 1:57 pmI’ve been traveling but I wanted to mention the three Buy List earnings reports that came after yesterday’s closing bell.
AFLAC ($AFL) had operating earnings of $1.51 per share. That was eight cents more than estimates. The currency exchange rate cost them four cents per share last quarter. As I’ve said, operationally, AFLAC is doing well.
AFLAC’s board raised the quarterly dividend from 37 to 39 cents per share. For Q4, AFL sees earnings ranging between $1.28 to $1.37 per share. That will give them full-year earnings between $6.14 to $6.23 per share. The stock broke $61 per share early today, but has pulled back.
Fiserv ($FISV) earned 86 cents per share which was two cents better than expectations. They now expect 2014 earnings per share between $3.34 and $3.38. That implies Q4 earnings between 86 and 90 cents per share. The Street had been expecting 89 cents per share. The shares got as high as $69.94 today.
Express Scripts ($ESRX) posted earnings of $1.29 per share which matched expectations. They also narrowed their full-year range to $4.86 to $4.90 per share. The previous view was $4.84 to $4.92 per share. The new full-year guidance means that the guidance for Q4 is $1.36 to $1.40 per share. The Street had been expecting $1.38 per share. -
Morning News: October 29, 2014
Posted by Eddy Elfenbein on October 29th, 2014 at 7:03 amDeutsche Bank Posts Loss of $117 Million in Third Quarter
World Bank Urges China to Cut Economic Growth target to 7% in 2015, Focus on Reforms
Safe-Deposit Box Craze Lays Bare Ukraine Woes After Vote
What Could the Fed Do to Address Inequality?
SEC Probing Private Equity Performance Figures
Shell Midstream Partners Raises $920 Million in New York I.P.O.
Facebook Projects ‘More Difficult’ Fourth Quarter
Record Smartphone Sales Fuel LG Electronics
Newest Workers for Lowe’s: Robots
New Total Chief o Visit Key Oil Contacts as Q3 Profits Dip
Weak Merck Sales Overshadow Third-Quarter Cost Cuts
Cullen Roche: Bond Market Narrative Fails
Joshua Brown: Bridging the Divide Between Finance and Technology
Be sure to follow me on Twitter.
-
The General’s Portfolio
Posted by Eddy Elfenbein on October 28th, 2014 at 11:17 amLately there’s been news that the former director of NSA, LTG Keith Alexander, has been investing in some obscure investments.
Why would the head of NSA buy (or sell) Potash Corp. of Saskatchewan ($POT)? That’s not the usual company that individual investors buy. Major producers of Potash are Canada and Russia, while China is a major consumer. Isn’t that a bit…odd?
Or what about the Aluminum Corp. of China ($ACL), which is often called Chalco for short? This is a state-controlled enterprise. We have to wonder if the spymaster had some inside info.
I’m afraid to disappoint you, but I have a very different answer. It’s just a guess, but I think my theory explains the general’s actions.
He was a subscriber to an investment newsletter — and most probably one with a momentum-based strategy. Both those stocks had soared during much of the last decade. They’re the kinds of things that look great on a track record.
Many investment professionals don’t know those stocks. They were probably picked up in some type of screener.
-
Durable Goods Fell 1.3% in September
Posted by Eddy Elfenbein on October 28th, 2014 at 10:59 amToday’s durable goods report was not a good one. The Commerce Department said that orders for durable goods fell 1.3% last month. Economists were expecting an increase of 0.5%.
Orders for non-defense capital goods excluding aircraft, a proxy for future business investment in items like computers, engines and communications equipment, dropped 1.7 percent, the most since January, after a 0.3 percent gain the previous month.
Shipments of non-defense capital goods, used in calculating gross domestic product, fell 0.2 percent after rising 0.1 percent.
The figures may prompt some economists to cut forecasts for third-quarter GDP. A report later this week is projected to show the world’s largest economy grew at a 3 percent annualized rate from July through September after a 4.6 percent gain in the previous three months that marked the best performance since the end of 2011, according to the median forecast of economists surveyed by Bloomberg.
On Thursday, we’re going to get our first look at Q3 GDP growth. I think the number will be over 3%.
Fortunately, the stock market is up again today. The S&P 500 broke above 1,970 for the first time since October 8. CR Bard ($BCR) is at a new 52-week high today. Fiserv ($FISV) and Moog ($MOG-A) are very close to new ones as well.
-
Morning News: October 28, 2014
Posted by Eddy Elfenbein on October 28th, 2014 at 6:54 amECB Fails 25 Banks in Stress Test; Problems Mainly at Smaller Ones
It’s Getting Worse In Germany: Confidence Falls To A 22-Month Low
Sweden’s Riksbank Cuts Key Rate to Zero as Deflation Fight Deepens
Toyota Tops Consumer Reports Reliability Rankings
SoftBank Begins $10 Billion India Investment Spree With Snapdeal Stake
Lloyds Takes $1.4 Billion PPI Charge, Shares Decline
BP Earnings Fall 18% in Third Quarter Amid Lower Oil Prices
Chiquita Agrees to $742 Million Buyout
Valeant Is Ready To Boost Its Bid For Botox-Maker Allergan
Merck on Track for $2.5 Billion in Cost Savings
Saab Signs $5.44 Billion Fighter-Jet Deal With Brazil
A Track Record for Making Money and Making a Difference
Discount-Hunting Shoppers Threaten Stores’ Holiday Cheer
Jeff Carter: Explaining Bitcoin to People That Want To Learn, But Are New
Epicurean Dealmaker: Courtly Love
Be sure to follow me on Twitter.
-
S&P 500 = 1,960
Posted by Eddy Elfenbein on October 27th, 2014 at 3:34 pmThe stock market has risen on six of the last seven trading days, but it looks like today may be another down day. Still, it will be close.
Our Buy List is having a mostly-good day. I was pleased to see Microsoft ($MSFT) do well on Friday after its earnings results. MSFT is mostly holding on to those gains today.
However, I was surprised to see Ford ($F) get punished so hardly on Friday. Shares of F have been below $13.70 today and on Friday. As I see, there wasn’t much new information in the earnings report. It was pretty much what was expected. At least, to anyone familiar with the company.
Tomorrow is a big day for earnings. AFLAC (AFL), Fiserv ($FISV) and Express Scripts (ESRX) are all due to report. Both Fiserv and CR Bard ($BCR) are at new 52-week highs today.
-
Archives
- November 2026
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His