-
Personal Finance 101
Posted by Eddy Elfenbein on August 8th, 2013 at 2:17 pmIt’s easy to laugh at the comic books put out by the Fed.
No, you didn’t read that wrong. The New York Fed really does have a series of comics, and they’re available both in free print versions and on its website. Included are such titles as “The Story of Banks,” “The Story of the Federal Reserve System,” “The Story of Foreign Trade,” “The Story of Monetary Policy”—you get the idea.
Not all the materials are technical, of course. “A Kid’s Guide to Money” attempts to teach budgeting to whatever generation is now replacing the Millennials in the long parade of evermore-entitled American self-seekers, while “Wishes and Rainbows” is more philosophical: A little girl finds the secret to raising colorful flowers in a black-and-white world. How to distribute them? Allow the market to dictate the price of scarce resources? Sell off the community’s wealth to more-developed neighbors with superior technology? From each according to his abilities, to each according to his means?
Granted, the Fed is making the satirist’s job pretty easy here. You don’t need to be super-hip to take campy delight in the books’ stodgy, unconsciously-patronizing-to-the-kids tone and cheesy graphics, which are pretty much what you’d expect from educational materials mandated by bureaucratic fiat. (Reading through them, you can almost hear the fluorescent lights humming in some grim federal building in the most forlorn corner of L’Enfant Plaza.) One activity book opens, “An old rock group called the Rolling Stones once sang….” Another features characters whose similarity to the stars of Hanna-Barbera’s Scooby-Doo franchise is just this side of legally actionable. Still another features two not-fun videogames (here and here).
But quickly the laughs give way to chagrin. And a dawning sense of alarm.
Why alarm? Because what quickly becomes apparent is that for all their lameness, these materials are trying to address a real need. Specifically, the need for financial literacy, which, on the evidence of certain events in the housing and credit markets of not too long ago, would appear to be sorely lacking in today’s America.
The Fed isn’t alone in throwing its hat into this educational ring. In 2011, Virginia’s public schools made a combined economics/financial-literacy class mandatory for graduation. Other states have similar requirements on the books. Meanwhile, many colleges now mandate that their charges take Personal Finance 101 immediately upon enrolling.
These curriculum changes may, of course, be motivated by whatever fad is now sweeping the graduate schools of Education and so filtering down to the state bureaucracies. But I prefer to reject such cynicism, however justified. I really want to believe that America’s public officials are indeed finally waking up to reality, that they recognize that in an increasingly post-pension world, a world where people are living longer and where Social Security cannot be relied upon to maintain one’s standard of living after retirement, the good citizens of the republic must, sad to say, learn to make intelligent decisions with their money. Nowadays this has become even more imperative, given that the country’s financial-services sector has become ever more aggressive—and ever more devious—in its strategies to separate folks from their hard-earned dollars.
Whatever the case, the teachers would appear to have their work cut out for them. A 2010 study by the University of Arizona found that college students all too frequently indulge in “risky coping strategies.” Among these “strategies”: postponing necessary health care and using one credit card to pay off another. Meanwhile, a financial-literacy workshop hosted by a community-outreach association in the Bronx tries to render its participants “work-ready.” Its activities include teaching 22-year-olds how to read their paychecks and explaining that check-cashing counters are frequently not the best option for those in need of funds. One attendee confessed she’d bought two pairs of headphones the day before the workshop, for reasons unclear even to herself. Several students were surprised to learn that credit cards are not a form of free money.
Astonishing, I know. But lest you come to the conclusion that such cluelessness could only flourish between East Tremont Avenue and the Bruckner Expressway, there is abundant evidence of its pervasiveness in all sectors of American society. Annamaria Lusardi, a Dartmouth economist who heads up the Financial Literacy center, has found that a majority of Americans do not understand the idea of compound interest. And Broke, U.S.A., journalist Gary Rivlin’s ground-level view of the Great Housing Scam of the 2000s, describes scores of people—rich, poor, and everything in between—who refinanced out of low-interest mortgages, or who thought they had signed fixed-rate agreements when they had really signed adjustable-rate ones.
When you combine this total lack of comprehension with Americans’ ever-growing sense of entitlement—our sense that not being able to pay for the things we want should be no impediment to our buying them—you have a disturbing sense that our culture that is in deep trouble.
Maybe the Fed is onto something, after all.
“A Kid’s Guide to Money,” page 4:
“We all have a limited amount of money that we can use to buy things. Sure, it would be nice to have whatever we want whenever we want it, but because money is scarce, we have to make choices. When you make a choice, you give up one thing in exchange for another thing. This is how adult life works.”
A sobering lesson. Would that we had learned it back in 2004.
-
Morning News: August 7, 2013
Posted by Eddy Elfenbein on August 8th, 2013 at 6:18 amEvery Country in Europe Should Be Glad It’s Not Greece
China Trade Rebounds in Further Sign Economy Stabilizing
Forget ‘Taper’ Risk: China is a Bigger Threat
BOJ Beat: 5 Takeaways From Kuroda News Conference
Every Country in Europe Should Be Glad It’s Not Greece
Tesla Motors Stock Soars After Operating Profit Beats Expectations
Facebook and Groupon Win Back Investors, Spur Rally
Silicon Valley Optimistic About Jeff Bezos Buying Washington Post
Turner, HBO and Warner Bros. Drive Time Warner to Strong Quarter
JPMorgan Reveals It Faces Civil and Criminal Inquiries
AOL to Buy Adap.tv, a Video Ad Platform, for $405 Million
Commerzbank Sees Signs of Growth
Deutsche Telekom Tops Sales Estimates, Boosts U.S. Spending
Cullen Roche: Japanese Sales Growth is Surging
Credit Writedowns: The Changing Debate Over China’s Economy
Be sure to follow me on Twitter.
-
What if the Stock Market Were a Bond?
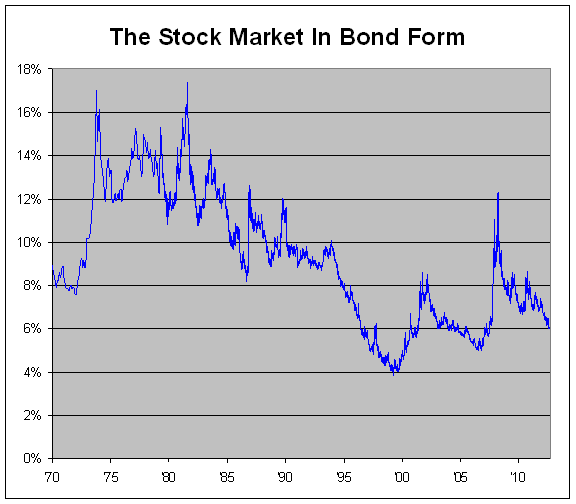
Posted by Eddy Elfenbein on August 7th, 2013 at 2:52 pmHere’s an update to one of my more off-the-wall ideas. I was curious to see what the historical performance of the stock market looks like, but in the form of a bond.
Crazy? Let me explain.
I took all of the historical market performance of the Wilshire 5000 (including dividends) and invented a hypothetical long-term bond that matched the market’s daily gains step-for-step.
I assumed that it’s a bond of infinite maturity and pays a fixed coupon.
There’s one hitch, though. I have to choose a starting yield-to-maturity for the beginning of the data series in December 1970. So this isn’t a completely kosher experiment because the starting point is based on my guess.
If I choose a number that’s too high, the historical performance won’t be able to keep up, and the yield-to-maturity would grow higher and higher and soon leave orbit. Conversely, if my starting YTM is too low, the yield would gradually get pushed down to microscopic levels.
Fortunately, the data makes my job easy. After four decades, the window I have to work with is pretty narrow. Starting with 10% is too high, and 8% is too low. After playing with the numbers, I finally settled on 8.93%.
Even though this “bond” is completely make-believe, it reflects what the actual stock market really did for the past 42-1/2 years. Through yesterday, the “bond’s” yield stood at 6.01%.
Here’s what the actual stock market looks like, expressed in the form of a bond:
-
“It’s Getting Crowded in Here”
Posted by Eddy Elfenbein on August 7th, 2013 at 11:17 amFord ($F) is hiring even more people:
Ford is expanding again.
This time, the country’s second-largest automaker is adding 800 jobs, primarily in vehicle development.
The move means Ford will add a total of 3,000 white collar jobs this year, with most of them located at the company’s headquarters in Dearborn, Mich.
“It’s getting crowded in here,” one Ford worker said at company headquarters. “I remember when there used to be a lot of empty desks and a lot of long faces.”
Not anymore. As Ford has expanded, it has filled those desks and turned massive losses into record profits.
-
The Legend That Is Starbucks
Posted by Eddy Elfenbein on August 7th, 2013 at 10:25 amWhenever I look at it, I always come away thinking that Starbucks ($SBUX) is insanely over-priced, yet the stock keeps proving me wrong. Roben Farzad of Bloomberg has some fascinating facts on SBUX:
More than 19,000 stores and four decades since it started up, Starbucks (SBUX) is still managing to bust out of its balance sheet, defying the law of large numbers.
In the coffee giant’s latest quarter, net income shot up 25 percent from a year ago, on a 13 percent gain in sales, hitting $3.74 billion. Global same-store sales gained 8 percent, well ahead of analysts’ average estimate of 5.8 percent, according to Consensus Metric. Free cash flow—money available to be reinvested in the enterprise, to retire debt, and to pay dividends or repurchase stock—will grow an enormous 50 percent in the year ending September 30, according to a Bloomberg survey of Wall Street analysts.
Consider: Starbucks’s revenue gain of 11.5 percent in the 12 months ended June 30 exceeded that of McDonald’s (MCD) by more than nine times. Consider also: Adjusted for splits, Starbucks was a 73¢ stock in 1992. It’s now worth $73 and sports a $55 billion market cap.
Bloomberg’s Charles Mead reports that Starbucks throws off more free cash relative to its debt than any U.S. restaurant chain. So flush is the Seattle company that it can more than double its debt, to reward shareholders, without hurting its credit. The company plans to add $750 million of debt to the $550 million of bonds it has outstanding—and could take out as as much as $1 billion without materially affecting its credit profile, according to Morningstar (MORN).
Starbucks, which carries an A- credit rating from Standard & Poor’s (MHP), would still have a safer debt-to-equity ratio than about 90 percent of indebted S&P 500 index companies. “They’re happy with that A- rating, but they do recognize that they do have some room to lever up,” Joscelyn Mackay of Morningstar told Mead. “This is a company where their balance sheet has gotten away from them in a positive sense, in that they’ve continued to grow and earnings have continued to grow, and they haven’t kept pace with it.”
“We’ve long recognized that there’s opportunity with an extremely conservative balance sheet to bring a bit of debt on,” Chief Financial Officer Troy Alstead said on a July 25 conference call. Indeed, of the 11 consumer-discretionary companies in the S&P 500 with market values bigger than $50 billion, Starbucks has the least debt. The No. 1 coffee chain is “in the early innings of a global expansion that may last for decades” and is set to benefit from lower coffee costs and higher-margin food sales, Goldman Sachs analysts led by Michael Kelter wrote in a July 26 report.
Props to Howard Schultz for turning around Starbucks since it announced his return to the CEO job in January 2008, after a year in which the share price was cut in half. It has since quadrupled.
The stock is currently going for more than nine times earnings and 27 times next year’s earnings. The dividend yield is just below 1.2%.
It’s a great company, but I think it’s just too pricey.
-
Morning News: August 6, 2013
Posted by Eddy Elfenbein on August 7th, 2013 at 6:16 amSteep Learning Curve Ahead for Next RBI Governor Raghuram Rajan
Under Carney, Bank Of England Moves To Forward Guidance
Easy Cash Ebbs for $300 Billion Asean Port-to-Rail Cost
Tapering of Stimulus Could Start as Soon as September, 2 Fed Presidents Hint
Obama Sketches Goals for Retooled Mortgage Market
SEC’s Hunt for Crisis-Era Wrongdoing Loses Steam
BofA Sued by U.S. Over Mortgage Securities
Gold Price Crash Will Not Hurt Our Plans, Says Highland Gold
Chevy Proves It Has Learned A Crucial Rule For Selling Electric Cars
In American Greetings Deal, Echoes of Larger Buyout for Dell
’Washington Post’ Needs Bezos’ Digital Midas Touch
Walt Disney to Lose Millions on Lone Ranger Film
Jeff Carter: Change Management, as it Relates to Startups
Phil Pearlman: how Do You Know When a Stock is Broken?
Be sure to follow me on Twitter.
-
Muppets Most Wanted
Posted by Eddy Elfenbein on August 6th, 2013 at 10:53 pm -
Buy List Earnings Calendar
Posted by Eddy Elfenbein on August 6th, 2013 at 2:47 pmStock Symbol Date Estimate Result JPMorgan Chase JPM 12-Jul $1.45 $1.60 Wells Fargo WFC 12-Jul $0.93 $0.98 Microsoft MSFT 18-Jul $0.75 $0.66 Stryker SYK 18-Jul $1.03 $1.00 CR Bard BCR 23-Jul $1.38 $1.42 CA Technologies CA 24-Jul $0.74 $0.78 Ford Motor Company F 24-Jul $0.37 $0.45 Moog MOG-A 26-Jul $0.84 $0.90 Fiserv FISV 30-Jul $1.44 $1.50 Harris Corporation HRS 30-Jul $1.15 $1.41 AFLAC AFL 30-Jul $1.51 $1.62 WEX Inc. WEX 31-Jul $1.04 $1.05 DirecTV DTV 1-Aug $1.34 $1.18 Cognizant Technology Solutions CTSH 6-Aug $0.97 $1.07 Nicholas Financial NICK 6-Aug na $0.46 That’s the end of our “June” cycle stocks on the Buy List. We had two companies that ended their quarter in July; Ross Stores ($ROST) and Medtronic ($MDT). Both stocks are due to report in two weeks.
The Credit Card Strategy at Wells Fargo
Posted by Eddy Elfenbein on August 6th, 2013 at 12:39 pmHere’s a new look at an old business:
Wells Fargo & Co, the fourth-largest U.S. bank, is trying to grow its relatively small credit-card business with an unusual strategy: appealing to its customers’ distaste for debt.
In 2007, Wells Fargo debuted the Home Rebate Card, which offers a 1 percent rebate that automatically goes toward paying down principal on a Wells Fargo home loan. In the coming months, the bank has plans to roll out cards that provide similar benefits to customers who have taken out student loans, auto loans and other types of consumer debt from the bank.
“The real thing customers wanted was to pay down their mortgage,” Tom Wolfe, Wells Fargo’s executive vice president for consumer credit solutions, said in a recent interview. “That created a thought process where we asked, ‘Why don’t we offer that service for all our products?'”
Wells Fargo believes offering such rewards cards is one of its best bets for boosting the credit card business at a time when consumers remain wary of taking on debt. Outstanding balances on credit cards and other types of revolving debt in the United States have remained flat over the past three years, Fed data show.
Only about one-third of Wells Fargo’s customers carry the bank’s own credit cards – a relatively small number for a bank that controls roughly 10 percent of all U.S. deposits and prides itself on selling customers multiple products. It is ranked eighth among U.S. credit card issuers, with purchase volume of $66 billion in 2012, compared to $566 billion at top-ranked American Express Co and $416 billion at second-place JPMorgan Chase & Co, according to the Nilson Report.
Nicholas Financial Earns 46 Cents Per Share
Posted by Eddy Elfenbein on August 6th, 2013 at 11:38 amNicholas Financial ($NICK) reports 46 cents per share for its fiscal Q1:
Nicholas Financial, Inc. announced that for the three months ended June 30, 2013 net earnings increased 5% to $5,700,000 as compared to $5,407,000 for the three months ended June 30, 2012. Per share diluted net earnings increased 5% to $0.46 as compared to $0.44 for the three months ended June 30, 2012. Revenue was $20,476,000 for the three months ended June 30, 2013 as compared to $20,428,000 for the three months ended June 30, 2012.
“Our results for the three months ended June 30, 2013 were positively affected by a non-cash gain related to interest rate swap agreements (mark-to-market) and were adversely effected by an increase in operating expenses,” stated Peter L. Vosotas, Chairman and CEO. During the June quarter we opened our fourth branch office in the South Florida market. “We will continue to develop additional markets and expect to open new branch locations during the remainder of our current fiscal year, which ends March 31, 2014.”
These numbers look pretty good to me. It looks like NICK benefited about four cents per share after-tax thanks to the interest rate swap agreement. I can’t find the details yet because it looks like there’s been an accounting change which adds about $3 million to quarterly revenues. Overall, these results are basically what I was expecting, so that’s good news.
Here’s a spreadsheet detailing detailing NICK’s last few quarters.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His