-
CR Bard’s Outlook for Q3
Posted by Eddy Elfenbein on July 23rd, 2013 at 10:11 pmFrom today’s earnings call:
Now moving to financial guidance. For Q3, we are expecting constant currency sales growth between 1% and 3%, excluding any royalties from Gore. Our original sales guidance for the year was 0% to 3% growth, excluding the Gore royalties, and we expect to be squarely within that range. With respect to the Gore timing, as Tim said, we still expect cash in hand prior to the end of 2013.
From an EPS standpoint, excluding items affecting comparability, we see the third quarter in the range of $1.37 to $1.41 per share. To be clear, this guidance reflects the fact that we don’t expect to have final resolution of the Gore matter this month. And as we previously discussed, that reduces adjusted EPS by about $0.30 per share for the quarter.
With respect to full year EPS guidance, we’ll be in a better position to update you once we have seen the rulings from the District Court. Also, I’ll just finish by reminding you that in conjunction with the announcement of the divestiture of our EP business, we told you that would be about $0.05 dilutive to 2013 EPS assuming a late Q3 close.
-
CR Bard Earned $1.42 Per Share for Q2
Posted by Eddy Elfenbein on July 23rd, 2013 at 4:18 pmHere come the earnings. CR Bard ($BCR) just announced Q2 earnings of $1.42 per share for Q2. That’s four cents more than expectations. Revenues rose 2.3% to $759.9 million which beat expectations by $9.8 million.
Timothy M. Ring, chairman and chief executive officer, commented, “Our operating results this quarter exceeded our expectations. We continue to focus on the execution of our investment plan, which we believe will shift the mix of our portfolio to faster growing products and geographies and contribute to long-term sustainable leadership positions in our markets.”
-
Two Stories to Highlight
Posted by Eddy Elfenbein on July 23rd, 2013 at 11:43 amWe’re coming up on noon, and the stock market opened just a tad higher, but we’re currently just a tad lower on the day. Volatility has really dropped lately. This morning, the $VIX was at its lowest level since April 12.
I have two small stories that I want to highlight. One is that Ford ($F) has announced it will hire 3,000 salaried employees which includes 800 white-collar jobs at HQ; “Global employment is up to 175K from a recession-low of 158K.”
The other is that Wells Fargo ($WFC) is crushing it in mortgage lending.
When a Wells Fargo stagecoach rolled through lower Manhattan two years ago to mark the rebranding of former Wachovia Corp. bank branches, some New Yorkers laughed. Rival bankers weren’t among them.
The San Francisco-based bank has become the dominant U.S. mortgage lender, grabbing an unprecedented 28.8% share of all home loans issued nationwide last year, up from 11.2% in 2007, the year before it bought Wachovia. Its home-loan production hit $524 billion last year, the largest annual total ever for one lender and greater than the output of the next five largest lenders combined, according to the publication Inside Mortgage Finance.
In the lucrative Manhattan market, Wells issued almost 20% of new home loans—almost equal to the volume of its two biggest competitors together, according to real-estate research firm CoreLogic Inc. In San Francisco, it made 21% of new loans, in Los Angeles, 12%, and in Dallas, 9%.
“They are dominating the retail space because they are huge, and because there is so little competition from other big banks that have pulled back,” says Alan Rosenbaum, chief executive of GuardHill Financial Corp., a New York-based mortgage bank.
-
Tech Has Badly Lagged
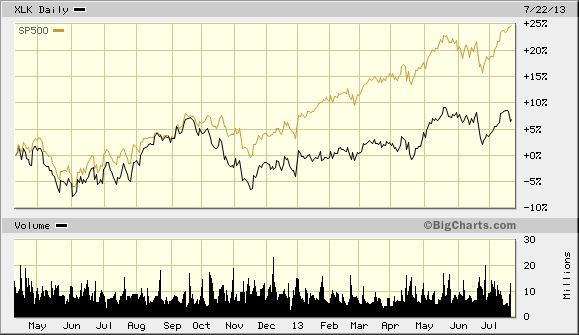
Posted by Eddy Elfenbein on July 23rd, 2013 at 9:33 amSince April 2012, the tech sector has badly lagged the rest of the market. Here’s the Tech Sector ETF ($XLK) compared with the S&P 500.
-
Half Expecting Tapering in September
Posted by Eddy Elfenbein on July 23rd, 2013 at 9:11 amThe U.S. stock market looks to rise again today thanks to news from China that authorities there are looking to help their economy avoid a hard landing. Media in China is reporting that the government will increase investment in railroad projects to offset slowdowns in important industrial sectors. Of course, by a slowdown in China, they mean 7% growth instead of 10%.
The big news today on Wall Street is that investors are on the edge of their seats waiting for Apple ($AAPL) to report earnings. It’s no surprise that a lot of folks love seeing Apple fail. Over the last few quarters, Apple’s growth rate has slowed down dramatically.
So far, 113 companies have reported earnings this season. Of that, 73% have beaten on earnings and 52% have beaten on sales. That’s pretty good. The only major outlier has been tech where earnings have been pretty bad. Tech has badly lagged the market for the last year.
Netflix ($NFLX) looks to open lower this morning by about 3.4% after a disappointing earnings report yesterday. I honestly don’t get NFLX. As I look at it, the stock is vastly overpriced.
According to a recent Bloomberg poll, half of economists expect the Fed to pare its bond purchases in September down to $65 billion per month from the current rate of $85 billion. Also, half of economists (not sure if it’s the same half) think the Fed will wrap up its bond buying by the middle of next year.Fifteen percent said tapering will start in October and 28% said it will be December. Interestingly, the yield on the 10-year bond has fallen lately. The yield had gotten as high as 2.72% two weeks ago. Yesterday, the bond closed at 2.49%.
I think one of Bernanke’s goals has to been to hammer away at the idea that bond purchases are a completely separate policy from interest rates. It’s taken Wall Street some time to get the message, but it’s come through.
-
Morning News: July 23, 2013
Posted by Eddy Elfenbein on July 23rd, 2013 at 6:35 amBRIC Bust Seen in Emerging Market Discontent With Growth
Mandela’s Wealth-Sharing Dream Fades in South Africa
Home Sales Take A Breather, But Prices Hit Five-Year High
New Powers Invoked to Curb a High-Speed Trading Feint
Telefónica to Buy E-Plus of Germany From KPN
UBS Reports Higher Profit, U.S. Mortgage Bond Settlement
Vivendi in Talks to Sell Maroc Telecom Stake to Etisalat
Strong Quarter for Netflix, but Investors Hit Pause
McDonald’s Grilled by Investors
DuPont Says May Sell Or Spin Off Paint Pigments Business
A Towering Fine for Naught, as the S.E.C. Tracks Cohen
Grants, Scholarships Now Play Leading Role In Paying For College, Topping Mom And Dad
Jeff Carter: What Would You Do To Improve Business TV?
John Hempton: It Was the Night Before Christmas…Falsifying Bill Ackman’s Herbalife Thesis
Be sure to follow me on Twitter.
-
AFLAC Breaks $60
Posted by Eddy Elfenbein on July 22nd, 2013 at 12:24 pmIn early 2011, shares of AFLAC ($AFL) got above $59 but were never able to crack $60. Today, they finally did.
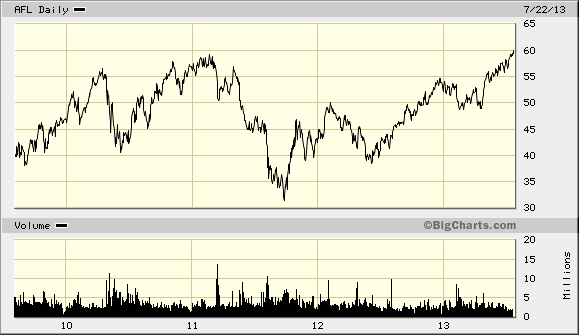
AFLAC has been as high as $60.15 today. The last time the stock was over $60 was September 2008.
-
The Dow Is Just 6% from a 10,000-Point Rally
Posted by Eddy Elfenbein on July 22nd, 2013 at 9:27 amI’m back in the office after a nice, relaxing week off. The stock market continued to rally while I was away, and the S&P 500 currently isn’t far from 1,700.
There’s going to be a lot more earnings news this week. So far, the overall earnings report has been pretty good although there have been some high-profile blunders. Microsoft ($MSFT), of course, is one. The stock got shellacked for an 11.4% loss on Friday. Fortunately, the other 19 stocks on our Buy List had outperformed the broader market on Friday. This is why I stress holding a diversified portfolio. You never know when one of your stocks will cause problems in the short term.
The Dow needs just another 6% for this to become a 10,000-point rally. We also crossed an interesting milestone last week. The S&P 500 now has $100 in earnings over the trailing 12 months. At the 1982 low, the whole index was going for $102. The S&P 500 first closed above $100 in in June 1968.
According to the latest numbers from S&P, the index is on track to earn $26.54 for Q2. That’s growth of just over 4% from last year’s Q2, but I think this will gradually be revised higher as earnings season grinds on. Wall Street currently expects the S&P 500 to earn about $109 this year and $123 next year. Again, the stock market is still reasonably valued going by most valuation metrics, and—this is a big “and”—assuming the future earnings projections are accurate. The S&P 500 raked in $97 last year. The earnings slowdown was very real but it seems to have ended last year. The only quarters with negative earnings growth were the third and fourth quarters of 2012.
One positive story for our Buy List is that Goldman has shifted Cognizant ($CTSH) from “neutral” to “buy.” I’m not exactly a fan of these upgrades and downgrades, but it’s nice to see that someone else agrees with you.
-
Morning News: July 22, 2013
Posted by Eddy Elfenbein on July 22nd, 2013 at 6:33 amGlobal Shares Eye Five-Year High After Abe Win, Yen Choppy
China’s Rate Reform May Serve To Shield Indebted State Firms
GSK Says Senior China Staff May Have Breached Law
Chinese Police Visit Astrazeneca, Question One Employee
Germany, Estonia Only Euro Zone Countries Cutting Debt In First Quarter
As WTI And Brent Reunite, Gulf Of Mexico Faces Squeeze, Not Glut
Gold Rush Trash Is Information Age Treasure
UBS Reports Higher Profit, U.S. Mortgage Bond Settlement
Philips Profit Jumps as Health-Care Orders Recover in the U.S.
Dell, Silver Lake Said to Disagree on Breakup Fee If LBO Fails
High-End Smartphone Boom Ending as Price Drop Hits Apple
For a Developing World, A Streamlined Facebook
Howard Lindzon: In Awe of the Mobil Global Warming Boom
Jeff Miller: Weighing the Week Ahead: It’s All About Earnings
Be sure to follow me on Twitter.
-
CWS Market Review – July 19, 2013
Posted by Eddy Elfenbein on July 19th, 2013 at 8:29 am“He who wishes to be rich in a day will be hanged in a year.” – Leonardo da Vinci
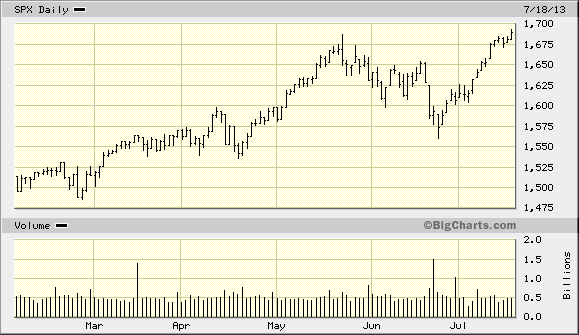
I’m currently enjoying a very relaxing week at Sebago Lake in Maine, but I have enough time to bring you up to speed on this week’s news on Wall Street. Of course, the big news is that earnings season marches on. It’s still early, but so far, 75% of the earnings reports for companies in the S&P 500 have topped estimates. That’s a very good “beat rate,” and it’s helped to power the market’s rally this week.
On Thursday, the S&P 500 broke out to an all-time intra-day high. It took us nearly two months to take out the old high. At one point on Thursday, the S&P 500 touched 1,693.12, which is a remarkable gain of 154% from the intra-day mega-low reached 52 months ago. Simply put, this has been one of the greatest bull markets in Wall Street history. More than 80% of the stocks in the S&P 500 are currently trading above their 50-day moving averages. What’s remarkable is that we’re hardly overvalued, according to most traditional valuation metrics.
As strong as the broader market has been, I’m also proud to report that our Buy List continues to do very well. Stocks like CR Bard, AFLAC, Harris Corp., Stryker and Fiserv all hit new 52-week highs on Thursday. Our Buy List is now up more than 22% for the year, and we had more good earnings news recently. In this week’s CWS Market Review, I’ll discuss the strong earnings reports we’ve had from our big bank stocks. I’ll also cover recent so-so earnings from Microsoft ($MSFT) and Stryker ($SYK). Plus, we have a bunch more earnings coming next week.
Strong Earnings Lift Our Banks to Multi-Year Highs
Right after I sent out last week’s CWS Market Review, JPMorgan Chase ($JPM) and Wells Fargo ($WFC) reported very strong earnings for Q2. JPM saw its earnings jump 31% from a year ago. Looking at the bottom line, the bank earned $1.60 per share for the quarter, which was 16 cents better than Wall Street’s consensus. After the earnings report, there was some predictable bellyaching that the strong results were largely due to lower loan-loss reserves. Please. When I hear people say that, I’m not sure they know how banking works. The truth is that JPM is doing very well right now.
Interestingly, the big wigs at JPM warned that higher mortgage rates are putting pressure on their margins. That’s not so surprising. The bank is currently working to cut many thousands of jobs in their community banking division. While these moves are painful and unpleasant, I think they’re ultimately needed. JPM’s CFO said that refi volume could fall as much as 40% if rates continue to rise.
Overall, I thought the earnings report was quite good, but the market seemed to have a slightly delayed reaction. Not until Thursday did the shares gap up to a 12-year high. Even after this year’s 28% rally, JPM is still going for less than 10 times this year’s earnings estimate. I like this stock a lot. I’m raising my Buy Below on JPMorgan Chase to $60 per share.
Also on Friday, Wells Fargo ($WFC) reported a 19% jump in Q2 earnings. For the quarter, WFC netted 98 cents per share, which was five cents more than the Street was expecting. That’s a big jump from the 82 cents per share Wells earned in last year’s Q2. Just like JPM, Wells said it expects to see a decline in its mortgage division. They’re planning on cutting jobs, as revenue growth was basically flat. Both banks made the right call by going into mortgages in a big way. Wealth management is one of the few areas where Wells is seeing some revenue growth. On Thursday, WFC finished the day at its highest close ever. These banks are very strong. This week, I’m raising my Buy Below on Wells Fargo to $48 per share.
Microsoft and Stryker Miss Earnings, but Don’t Worry
After the closing bell on Thursday, Microsoft ($MSFT) reported earnings of 66 cents per share, which was nine cents shy of estimates. The stock dropped more than 6% in the after-hours market.
The problem for the software giant is that PC sales are slowing, and that hurts their Windows business. This was a disappointing report, but what surprised a lot of people is that the company took a $900-million charge for its large inventory of unsold Surface tablets. This is the version of the tablet which runs on chips designed by ARM Holdings. The Surface has mostly been a flop. Last week, MSFT said it’s cutting prices to get more buyers, but that looks to be an uphill battle.
Microsoft knows it has a lot of work to do, and that was part of their big reorganization announcement. The tech giant had top-line growth of 10%, which was also below expectations. This was an ugly earnings report, but our investment thesis continues to hold—Microsoft’s price is lower than its value. I’m disappointed by these results, but I’m not ready to ditch the stock just yet. Microsoft remains a value buy up to $38 per share.
Stryker ($SYK) had some mixed earnings news. After the closing bell on Thursday, the orthopedic company reported second-quarter earnings of $1 per share, which was three cents below consensus. The good news was that revenues rose 5% to $2.21 billion, which was slightly better than consensus. Stryker also lowered its full-year guidance from $4.25 to $4.40 per share to a range of $4.20 to $4.26 per share. Frankly, that’s less than I had been expecting, but not much less. The company said that it’s getting squeezed by currency exchange rates, which is the kind of transient problem that doesn’t concern me so much. They lost four cents per share last quarter due to forex. Stryker also said that revenue growth for the year should range between 4% and 5.5%, which is slightly better than consensus. Stryker continues to be a very good buy up to $71 per share.
We Have Four Buy List Earnings Reports Next Week
The earnings parade continues. Four of our Buy List stocks are due to report next week. Please note that the earnings dates I’m listing here are tentative and may be off by a day or two. I’ll continue to have the latest earnings info at the blog. On Tuesday, CR Bard ($BCR), CA Technologies ($CA) and Ford Motor ($F) are due to report earnings. All three stocks have been doing very well for us lately. Ford has been especially strong; the shares got as high as $17.25 per share this week. Then on Friday, July 26, Moog ($MOG-A) will report its fiscal Q3 earnings.
Wall Street currently expects Q2 earnings of $1.38 per share from CR Bard ($BCR). Three months ago, the company told us that earnings would range between $1.35 and $1.39 per share. At the time, that was a disappointment, since the Street had been expecting $1.46 per share. To be fair, Bard had already said that 2013 will be a tough year for them, but they expect to make up the slack in 2014. Last month, Bard raised its dividend by 5%. Traders still like BCR a lot; the stock has rallied 14% since the beginning of May. My advice to investors is, don’t chase Bard. The stock remains a good buy up to $115 per share.
On Monday, CA Technologies ($CA) finally hit $30 per share. The stock is now a 35% winner on the year for us. Three months ago, the company had a blow-out earnings report. CA beat Wall Street’s consensus by more than 23%. I’m not expecting such a strong repeat. This time, Wall Street expects earnings of 71 cents per share. CA is a very good buy up to $31 per share.
Of all the companies reporting next week, I’m the most optimistic about Ford Motor ($F). In April, the automaker earned 41 cents per share, which was four cents more than consensus. This time around, Wall Street again expects 37 cents per share. I think Ford will easily beat that. Once Europe gets back on its feet, Ford will really prosper. Ford is an outstanding buy up to $18 per share.
Finally, Moog ($MOG-A) is due to report earnings next Friday. This stock has quietly become our best performer in 2013, with a 40.4% YTD gain. Moog expects full-year earnings of $3.55 to $3.65 per share, but will be dinged 15 cents per share in restructuring costs. For now, I want to keep a tight leash on the stock. Moog is a good buy up to $57 per share.
That’s all for now. More earnings reports are due next week, including four Buy List stocks. We’ll also get an important economic report on orders for durable goods. We’ll also get reports on new home sales and existing home sales. It will be interesting to see what the impact has been of higher mortgage rates on the housing sector. Be sure to keep checking the blog for daily updates. I’ll have more market analysis for you in the next issue of CWS Market Review!
– Eddy
-
Archives
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His