-
Wells Fargo Raises Dividend By 14%
Posted by Eddy Elfenbein on January 22nd, 2013 at 4:26 pmAfter the close, Wells Fargo ($WFC) announced that it’s raising its quarterly dividend from 22 cents to 25 cents per share. The bank will now pay out $1 for the whole year. Going by today’s close, that’s a yield of 2.85%.
Wells Fargo & Company (WFC) today announced a quarterly common stock dividend of $.25 per share, an increase of three cents, or 14 percent, per share from the prior quarter. The dividend is payable March 1, 2013, to stockholders of record on February 1, 2013, as approved today by the Wells Fargo board of directors. Wells Fargo has approximately 5.3 billion shares outstanding.
This dividend increase for the first quarter of 2013 was part of the company’s 2012 Capital Plan that the Federal Reserve did not object to in March, 2012. Wells Fargo submitted its 2013 Capital Plan on January 4, 2013, and it is currently under review by the Federal Reserve.
“The dividend increase approved by our board today was included in our 2012 Capital Plan and reflected the confidence we have in our company’s performance,” Chairman and CEO John Stumpf said. “We remain committed to returning more capital to our shareholders. We requested an increase in capital distributions in our 2013 Capital Plan as compared to our 2012 plan, subject to review and non-objection by the Federal Reserve Board.”
The Fed still needs to sign off on these dividend increases for many banks. Wells will have no trouble covering this dividend. If the earnings projections for this year are correct, Wells is passing on just 27% of its profits in the form of dividends.
-
Apple In Terms of Google
Posted by Eddy Elfenbein on January 22nd, 2013 at 1:26 pmI admit this chart doesn’t mean much of anything but I was just curious to see it. This chart shows the price of Apple divided by the share price of Google. In other words, Apple in terms of Google.
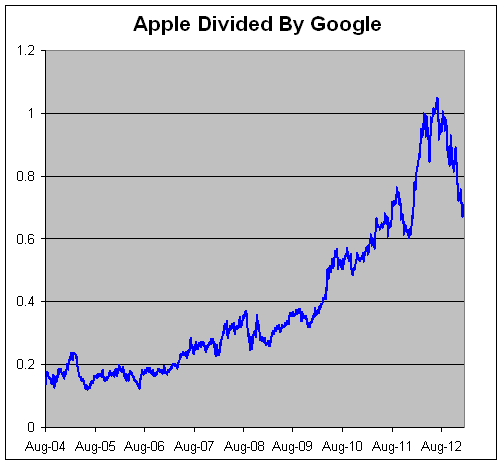
Apple has about three times as many shares outstanding as Google.
-
Earnings Season Numbers
Posted by Eddy Elfenbein on January 22nd, 2013 at 12:46 pmIt’s still early but here are some numbers about this earnings season. The current consensus is for the the S&P 500 to earn $25.18 which is an increase of 6.1% over the Q4 from 2011.
For all of 2012, the S&P 500 is expected to earn $98.85. That’s only a slight increase over the $96.44 from 2011. For 2013, the current consensus is for the index to earn $112.49.
The current divisor for the S&P 500 is about 8.93 billion, so just multiply that to any of the figures I’ve given above and you can see the total dollar amount.
-
How Closely Tied Are Stocks and the Economy?
Posted by Eddy Elfenbein on January 22nd, 2013 at 11:33 amNot as much as you’d think.
Here’s a look at the annual nominal change in GDP (running along the bottom) with the change in the S&P 500 (running vertically).

I didn’t run a regression, but just by eyeballing the results, the correlation looks pretty weak. This shouldn’t be too surprising. For one, the stock market is concerned with corporate profits, not the overall economy. Secondly, the stock market usually runs about six to nine months ahead of the economy. Finally, of course we know that the market can simply leave the realm of fair value entirely.
-
Yes, Now Investors Are Bullish
Posted by Eddy Elfenbein on January 22nd, 2013 at 10:48 amWhat happens after a 3.8-year-old bull market?
Bloomberg: Investors Are Most Optimistic on Stocks in 3 1/2 Years
International investors are the most bullish on stocks in at least 3 1/2 years, with close to two- thirds planning to raise their holdings of equities during the next six months, according to a Bloomberg survey.
As the global financial and business elite gather in Davos for their annual forum, 53 percent of respondents to the Bloomberg Global Poll also say equities will offer the highest return in the next year. That’s a 17 percentage point jump from the last poll in November and the most since the quarterly survey of investors, analysts and traders who subscribe to Bloomberg began in July 2009.
Behind the enthusiasm for shares: growing confidence in the U.S. economy and ebbing concerns about Europe. America is in its best shape in two years, according to the poll, with a majority of the 921 surveyed on Jan. 17 describing the economy as improving. In a sign the euro-area’s three-year debt crisis is easing, only 45 percent said the region’s economy is still deteriorating, down from seven in 10 two months ago.
“There does appear to be some cautious optimism that things are slowly being resolved,” Ben Kelly, an equity analyst at Louis Capital Markets in London and a poll participant, said in an e-mail. “There are some positive shoots that people are grabbing on to.”
I think the underlying story is that people are finally getting fed up with the low yields in bonds and they’re starting to leave. This is part of what I’ve talked about recently as fear is slowing melting away from this market.
-
S&P 500 Comes Within 1% of 1,500
Posted by Eddy Elfenbein on January 22nd, 2013 at 10:37 amThe stock market is holding on to some small gains this morning ahead of some major earnings announcements today. At one point, the S&P 500 got as high as 1,486.34. That’s just 1% away from 1,500.
On Friday, the $VIX plunged down to 12.26 during the day, though it’s back over 13 today. I’ve backed-tested the numbers and found that 13 is the magic number for the VIX; the stock market has performed much better below that number than above it.
One of our former Buy List stocks, Johnson & Johnson ($JNJ), reported earnings above Wall Street’s consensus, but the company guided below analysts’ forecasts for the year. The Street had been expecting $5.49 per share but JNJ said EPS will range between $5.35 and $5.45 for 2013. As much as I like the company, I think shares of JNJ are a bit overpriced here.
-
Morning News: January 22, 2013
Posted by Eddy Elfenbein on January 22nd, 2013 at 6:29 amMarkets Tumbling, Yen Soaring After Historic Move By The Bank of Japan
Euro Area Grapples With ESM Rules as Legacy Assets Loom
German Investor Confidence Increases to 2 1/2-Year High
Spain Escapes Aid But Doubts Remain
UK Credit Rating Under Threat As Borrowing Rises Again
Greece’s New Loan Payout Cleared by Euro Area Signals Optimism
U.N. Agency Warns of Rising Unemployment
Prophesies Made in Davos Don’t Always Come True
With Tax Advantages Looking Shaky, Private Equity Seeks a New Path
Profits at $1 Trillion Meet Valuations as S&P 500 Rallies
Atari’s U.S. Division Files for Bankruptcy, Hoping for a Sale
GM’s Girsky Says Major Cost Cuts Still Needed At Opel
Early Sales Tempered With Caution at Sundance
Jeff Carter: Microeconomic Mondays-Perfect Competition, Producer Surplus
Joshua Brown: New Secular Bull: Yes or No?
Be sure to follow me on Twitter.
-
Morning News: January 21, 2013
Posted by Eddy Elfenbein on January 21st, 2013 at 6:35 amEuro Ministers Set to Clash Over Terms of Channeling Aid
In Davos, Atmosphere for Bankers Improves
France Lifts Doubt Over Dutchman As New Eurogroup Head
Best Facebook Analyst Jobless Amid Kazakh Brokerage Cull
The China Miracle: A Rising Wealth Gap
An Overture From China Is Yet to Win Hollywood
JPMorgan Embraces Offshore Yuan as Trading Doubles
Dell Close To $22 Billion Leveraged Buyout Amid Decline In PC Market
$11.2 Billion Thai Bid Poised to Win Singapore Conglomerate
Huawei Pledges Openness To Woo Critics
What Went Wrong at Boeing: My Two Cents
Unusual Roots for Firm in Caterpillar Scandal
Finance Least-Trusted Industry for Third Year in Edelman Survey
Cullen Roche: Black Rock: The 2013 Macro View
Roger Nusbaum: The Big Picture for the Week of January 20, 2013
Be sure to follow me on Twitter.
-
RIP: Stan “The Man” Musial
Posted by Eddy Elfenbein on January 20th, 2013 at 1:27 pmMusial had 3,630 career hits; 1,815 came at home and 1,815 came on the road.
-
Cramer Was Right
Posted by Eddy Elfenbein on January 18th, 2013 at 1:48 pmThe Federal Reserve released the full transcripts of their meetings from 2007 today. While the minutes are released a few weeks after each meeting, the public can’t see the whole transcript for until five years have passed. That’s why we’re getting 2007 today.
In August of 2007, Jim Cramer made news with his famous “they know nothing rant” on CNBC. While he was broadly mocked for his outburst, Zachary Shrier makes a good point — Cramer was right. The Fed was clueless. The one from August 7th is particularly damaging,
I have talked to the heads of almost every one of these firms in the last 72 hours and he has NO IDEA what it’s like out there. NONE! And Bill Poole, he has NO IDEA what it’s like out there. My people have been in this game for 25 years and they’re LOSING THEIR JOBS and these firms are gonna GO OUT OF BUSINESS and it’s nuts. They’re NUTS! They know NOTHING! This is a different kinda market. And the Fed is ASLEEP. Bill Poole is a shame, he’s SHAMEUL! He oughta GO, and READ the Accredited Home document, at least I READ the darn thing.
Here’s Dennis Lockhart speaking during the meeting of August 7, 2007:
In the past few days, I have had substantive conversations with some well-positioned credit market observers, including managers of large investment portfolios, suggesting that the skittishness of financial markets is not likely to abate until later this fall. They have suggested that the choppiness in financial markets will be the rule in the near term and, very important, that the threshold for what constitutes a shock is now much lower than usual. I believe that the correct policy posture is to let the markets work through the changes in risk appetite and pricing that are under way, but the market observations of one of my more strident conversational counterparts—and that is not Jim Cramer [laughter]—are worth sharing. This party sees problems in the subprime structured debt market spreading to the CLO leveraged-loan market and, in a knock-on effect, to repo and commercial paper markets as well as to investment-grade corporate credit. This party points to nonprice rationing, commercial paper rollover risk, and general CDO contagion caused by the damaged credibility of rating agencies and contraction of collateral values. This party argues that treating the widening of credit spreads as normalization ignores substantial subsurface potential dislocations as evidenced by the collapse of American Home Mortgage Corporation. All that said, another counterpart noted a large pool of money now on the sidelines that is ready to provide financing for reasonable deals if prices fall low enough. Importantly, a large portion of this money comes from reliable long-term sources of investment, pension funds and insurance companies. Notwithstanding some descriptive rhetoric, this is not the credit crunch of the late 1980s, when the traditional financial intermediaries were strained for capital. The traditional investors are still out there with substantial liquidity, and they are just temporarily on the sidelines for understandable reasons and, barring further shocks, should return to the markets in force later this fall. The dislocations in the financial markets call for a posture of vigilant monitoring of developments but nothing more for now.
-
Archives
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- September 2017
- August 2017
- July 2017
- June 2017
- May 2017
- April 2017
- March 2017
- February 2017
- January 2017
- December 2016
- November 2016
- October 2016
- September 2016
- August 2016
- July 2016
- June 2016
- May 2016
- April 2016
- March 2016
- February 2016
- January 2016
- December 2015
- November 2015
- October 2015
- September 2015
- August 2015
- July 2015
- June 2015
- May 2015
- April 2015
- March 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- September 2014
- August 2014
- July 2014
- June 2014
- May 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- June 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- February 2009
- January 2009
- December 2008
- November 2008
- October 2008
- September 2008
- August 2008
- July 2008
- June 2008
- May 2008
- April 2008
- March 2008
- February 2008
- January 2008
- December 2007
- November 2007
- October 2007
- September 2007
- August 2007
- July 2007
- June 2007
- May 2007
- April 2007
- March 2007
- February 2007
- January 2007
- December 2006
- November 2006
- October 2006
- September 2006
- August 2006
- July 2006
- June 2006
- May 2006
- April 2006
- March 2006
- February 2006
- January 2006
- December 2005
- November 2005
- October 2005
- September 2005
- August 2005
- July 2005
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His