-
Medtronic Raises Dividend for 35th Year in a Row
Posted by Eddy Elfenbein on June 22nd, 2012 at 6:11 amI recently said that I expected Medtronic ($MDT) to raise its dividend for the 35th year in a row. Sure enough, the company announced today that it’s raising its dividend from 24.25 cents per share to 26 cents per share. Going by yesterday’s close, Medtronic yields 2.75%.
-
CWS Market Review – June 22, 2012
Posted by Eddy Elfenbein on June 22nd, 2012 at 5:33 amWith investing, sometimes you’re wrong even when you’re right. In last week’s CWS Market Review, I made a bold prediction. I said that Bed Bath & Beyond ($BBBY) could earn as much as 88 cents per share which was well above both Wall Street’s consensus of 84 cents per share and the company’s own guidance of 79 cents to 83 cents per share.
Well, my bold forecast was right. In fact, it wasn’t optimistic enough! Bed Bath & Beyond reported fiscal Q1 earnings of 89 cents per share. The problem is that they gave Q2 guidance of 97 cents to $1.03 per share which was below the Street’s consensus of $1.08 per share.
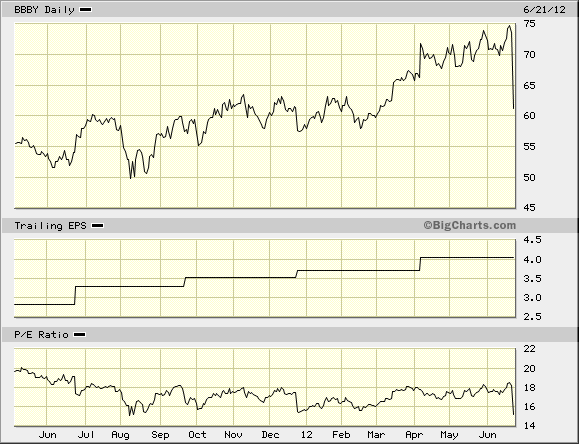
That’s all it took to unleash the bears. On Thursday, traders gave the stock a super-atomic wedgie. When the closing bell sounded, BBBY had lost $12.50, or 17% of its value. Ouch!
In this week’s issue of CWS Market Review, I’ll talk more about the outlook for BBBY. (Here’s a preview: Thursday’s selling was way, way, WAY overdone.) We’ll also look at the positive earnings report from Oracle ($ORCL). Put it this way: Things are going so well for Larry Ellison that he just bought his own Hawaiian island. (I’m serious.) But first, let’s try to deconstruct the damage at Bed Bath & Beyond.
Bloodbath & Beyond: 17% Loss in One Day
Let’s start with the good news. Bed Bath & Beyond reported solid earnings for the first quarter of their fiscal year (March, April and May). The company earned 89 cents per share which is a 24% increase over the 72 cents per share from last year’s Q1. That’s very good growth in this economy. Sales rose 5.1%, and the key metric for retailers, same-store sales, rose by 3%. That’s a good number although it’s down from 7% last year. The company was also helped by a tax benefit.
Bed Bath & Beyond has been buying back its stock at a furious pace. They spent $306 million during the first quarter to buy back 4.6 million shares. That’s roughly 2% of the outstanding shares. As I’ve said before, I’m not a fan of share repurchases. I’d rather see companies pass those profits on to shareholders in the form of dividends. Still, these numbers give you an idea of how profitable BBBY has been. In fact, they still have another $600 million left in the current share repurchase program. (Hey guys, how about a dividend?)
The company experienced a small drop in gross margins (40.6% to 40.0%) during Q1 which was due to the use of coupons. Still, BBBY has done a very good job of growing its margins over the past few years so I’m not concerned by a minor downtick. What’s far more important is that BBBY has a rock-solid balance sheet which includes $1.8 billion in cash, cash equivalents and investment securities.
As I mentioned last week, BBBY has made some impressive strategic acquisitions lately. They recently picked up Linen Holdings, and a few weeks ago they bought Cost Plus. Combined, these deals cost $650 million. In my opinion, these were very good moves. On an accounting note, BBBY said that once the Cost Plus deal is done, it will subtract several cents off their Q2 earnings but would be slightly accretive to second-half earnings.
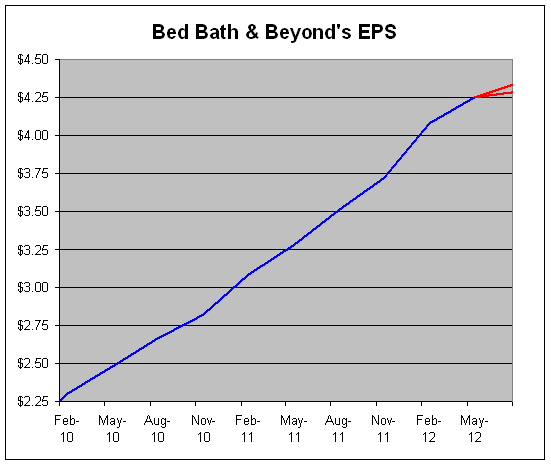
Now let’s look at the bad news. On the earnings call, BBBY said they expect fiscal Q2 earnings to range between 97 cents and $1.03 per share. Wall Street has been expecting $1.08 per share. The company also said it expects earnings for the fiscal year, which is 53 weeks long, to rise by a “high single-digit to a low double-digit” rate. This isn’t news—it’s an exact repeat of what they said in April. Let’s say this means growth of 8% to 12%. Last year, BBBY earned $4.06 per share so the guidance works out to a range of $4.38 to $4.55 per share. The Street had been expecting $4.63 per share which represents growth of 14%.
The guidance is disappointing, but please, it’s hardly that dramatic. In percentage terms, we’re only talking about a few points. On top of that, we know that BBBY has been beating its estimates pretty handily for the past several quarters. Consider these stats: Last quarter, they beat their own guidance by ten cents on the low end and six cents on the high end. For Q4, BBBY topped their guidance by 20 cents on the low end and 15 cents on the high end!
Doesn’t this suggest that this company likes to lowball Wall Street? Nothing in the past few months has greatly altered BBBY’s business. Remember, these are the folks who remained profitable during an historic housing bust; not all home furnishings stores can say that.
Going by Thursday’s closing price, BBBY is trading at roughly 13.5 to 14.0 times this year’s estimate. That’s a good deal. I apologize for the dramatic price swing, but the stock market isn’t always so cooperative. Due to Thursday’s big fall, I’ve decided to lower my buy price. I now rate Bed Bath & Beyond an excellent buy anytime the shares are below $70.
Reynolds American Hits New All-Time High
Before I get to Oracle’s earnings report, here’s a reminder of why we prefer high-quality stocks—and this is why I’m not worried about Bed Bath & Beyond. Two months ago Reynolds American ($RAI) posted disappointing earnings. They missed estimates by a grand total of two pennies per share. However, as I noted at the time, they kept their full-year forecast the same (just like BBBY). Sure enough, traders ignored the important stuff and latched on to the negative news. The market knocked 5% off the stock. I said that this made no sense and we shouldn’t be rattled by these short-term reactions.
So what’s happened since then? In the last two months, Reynolds American has raised its quarterly dividend and the stock has made up all the ground it lost and then some. On Wednesday, shares of RAI hit a new all-time high. Once again, patience and careful stock selection won in the end.
Oracle Can Reasonably Be a $40 Stock
On Monday, Oracle ($ORCL) surprised us by releasing their earnings report earlier than expected. The company earned 82 cents per share for the fourth quarter of their fiscal year. Oracle had told us to expect earnings to range between 76 cents and 81 cents per share. Wall Street’s consensus was for 78 cents per share. Revenue rose 1.3% to $10.9 billion which was inline with the Street. For the entire fiscal year, Oracle earned $2.46 per share. Oracle’s board also approved adding $10 billion to the company’s share repurchase program.
Oracle’s stock responded by jumping as high as $28.75 on Tuesday. After Thursday’s market downdraft, the shares closed at $27.81 which is still a very good bargain.
On the earnings call, Oracle said it sees fiscal Q1 earnings ranging between 51 and 55 cents per share. I think that’s probably a bit too low. Right now, Wall Street thinks Oracle can earn $2.66 per share for the entire fiscal year. That means the stock is going for a little over 10 times earnings. I honestly think Oracle can be a $40 stock. I’m raising my buy price to $32 per share.
That’s all for now. Next week is the final week of the second quarter. Can you believe the year is already half over? Historically, this has been a good time for stocks. Be sure to keep checking the blog for daily updates. I’ll have more market analysis for you in the next issue of CWS Market Review!
– Eddy
P.S. I recently sat down for an interview with Brian Richards of The Motley Fool. It was nice to have time to give detailed answers to questions on investing. You can see clips of our talk here, here, here, here and here.
-
Morning News: June 22, 2012
Posted by Eddy Elfenbein on June 22nd, 2012 at 4:52 amEuro Chiefs Spar On Greek, Spanish Aid
Spain’s Banks Need Up To $78 Billion, Report Shows
Manufacturing Shrinks In China & Eurozone, Slows In US
U.S. and Switzerland Reach Deal on Sharing of Financial Account Data
IMF Sees Euro Crisis At Critical Stage, Sees Bank Stress
Bank Investors Dismiss Moody’s Cuts As Years Too Late
Home Resales Decline While Fewer File Claims for Jobless Benefits
US Factory, Jobs Data Highlight Struggling Recovery
Bed Bath & Beyond: Slowed Growth, But Avoid Cleaning House Entirely
Rosneft In Talks To Join Exxon In Iraq
What To Expect From A Sinopec-Chesapeake Deal
As Facebook Seeks Answers, S.E.C. Investigates Exchanges
Joshua Brown: Involuntary Bankslaughter
Stone Street: How I Legally Caused BAC To Lose $4,000 On My Mortgage
Be sure to follow me on Twitter.
-
Higgs Boson on Intrade
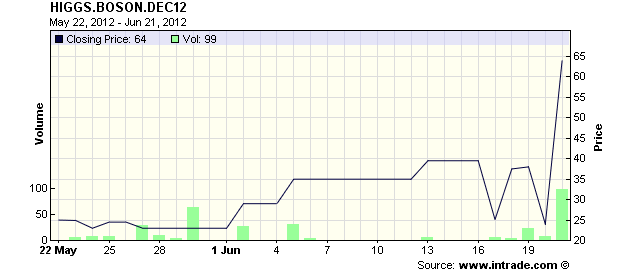
Posted by Eddy Elfenbein on June 21st, 2012 at 2:17 pmIntrade, the futures market for real world events, has a contract on whether a Higgs Boson Particle will be observed before the end of the year. The trade in this contract spiked up dramatically recently. (See Physics Community Afire With Rumors of Higgs Boson Discovery at Wired.)
Ironically, even though the contract is gapping up on heavy volume, it still has no mass. (BWAHAHAHA!)
-
Good Time in the Election Cycle
Posted by Eddy Elfenbein on June 21st, 2012 at 1:01 pmThe market adage “sell in May and go away,” worked well this year for about one month. However, the end of May during an election year has often been a good time to buy stocks.
A few years ago, I took all the data and calculated the average market during a Presidential Election Cycle. Historically, a low point has come on May 29th of the election year.
From there until August 3rd of the post-election year, the Dow has gained an average of 23.2%. That’s very impressive for just 14 months.
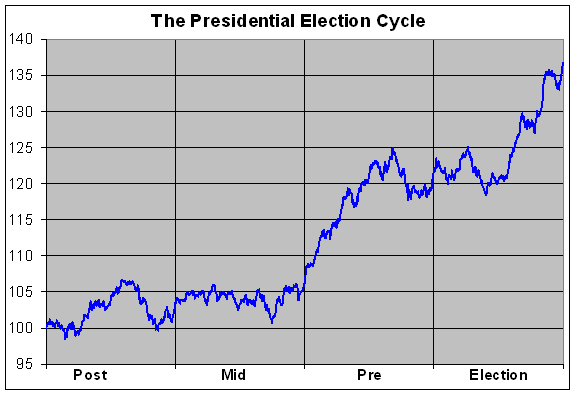
Let me add that I don’t make investment decisions based on these calendar effects. After all, this is an average of 115 years’ worth of data. I just think it’s fascinating how the market has behaved historically.
-
Bloodbath & Beyond
Posted by Eddy Elfenbein on June 21st, 2012 at 10:04 amShares of Bed Bath & Beyond ($BBBY) are getting crushed today. The stock has been as low as $62.23 this morning.
I think this is an absurd overreaction. Combined with yesterday’s drop, the shares are down 16.72% since Tuesday’s close.
Just to be clear, the midpoint of BBBY’s guidance was eight cents below Wall Street’s consensus. The market is translating that into a loss of over $12.
-
Staring Down the Bear Market
Posted by Eddy Elfenbein on June 21st, 2012 at 9:10 am -
Morning News: June 21, 2012
Posted by Eddy Elfenbein on June 21st, 2012 at 8:07 amGreece Faces Downgrade To Emerging Market Status By MSCI
Manufacturing Slump Deepens From Euro Area To China
Spain Borrowing Costs Peak As EU Ponders Bank Aid
Spanish Bond Sale Reveals Fragility of Economy
Oil Drops Below $80 To 8-Month Low On U.S. Supply, Europe
Bernanke Signals More Easing Likely If Job Growth Wanes
Bosses Rein In Banker Who Golfs With Obama
Facebook Stock’s Bad Start Reins In Short Sellers
Key Euribor Rate Eases As Coeure Says ECB To Discuss Cut
Cabot To Buy Dutch Company Norit For $1.1 Billion
China Iran Oil Imports Recover, Recoup Earlier Fall
BlueMountain Said To Help Unwind JPMorgan’s Whale Trades
Peugeot Examining Impact Of GM On BMW Hybrid Alliance
Cullen Roche: Money Supply Update – Still No Inflation Here Either…
Roger Nusbaum: Beware Overconfidence!
Be sure to follow me on Twitter.
-
Bed Bath & Beyond’s Earnings Call
Posted by Eddy Elfenbein on June 20th, 2012 at 11:45 pmFrom Seeking Alpha, here are some highlights from Bed Bath & Beyond’s ($BBBY) earnings call:
Based on these and other planning assumptions, we are modeling net earnings per diluted share to be approximately $0.97 to $1.03 for the fiscal second quarter of 2012. For all of fiscal 2012, including the benefit of the 53rd week and the incremental operating cost from the previously discussed major initiatives, we continue to model net earnings per diluted share to increase by a high single-digit to a low double-digit percentage range over fiscal 2011.
(…)
Our balance sheet and cash flows remains strong. We ended the fiscal first quarter with cash and cash equivalents and investment securities of approximately $1.8 billion. Assuming the completion of the Cost Plus transaction in our fiscal second quarter, we would expect the cash used in our fiscal second quarter for both the Linen Holdings and Cost Plus acquisitions to be approximately $650 million.
As of May 26, 2012, inventories at cost were approximately $2.2 billion or $60.63 per square foot, an increase of approximately 2.4% on a per square foot basis over the end of last year’s first quarter. Inventories continue to be tailored by store to meet the anticipated demands of our customers and are in good condition.
Consolidated shareholders equity at May 26, 2012, was approximately $3.9 billion, which is net of share repurchases, including the approximately $306 million, representing approximately 4.6 million shares repurchased during the fiscal first quarter of 2012. As of May 26, 2012, the remaining balance of the share — of the current share repurchase program authorized in December 2010 was approximately $613 million.
The company repurchased 2% of its outstanding stock last quarter.
-
The Buy List So Far
Posted by Eddy Elfenbein on June 20th, 2012 at 10:50 pmOur Buy List has beaten the S&P 500 for the last five years in a row. But this year so far, we’re trailing the market just slightly.
Through June 20th, our Buy List is up 7.74% while the S&P 500 is up 7.80%. That’s a gap of only 0.06%.
Including dividends, our Buy List is up 8.83% for the year while the S&P 500 is up 8.90%. The margin is so close that 18 more cents in Nicholas Financial’s share price would put us ahead of the market.
As usual, I’m in for the long haul so I’m confident that we’ll be ahead of the market once again at the end of the year.
 Eddy Elfenbein is a Washington, DC-based speaker, portfolio manager and editor of the blog Crossing Wall Street. His